Future of Algorithmic Trading: Trends to Watch
The future of algorithmic trading is about better research, richer data and more reliable execution—not a single technology that predicts every market move. AI-assisted development, language-based analytics, specialized infrastructure and stronger monitoring are changing how trading systems are built. Quantum computing is also producing experiments worth following, with results that require careful interpretation.
For traders, the useful question is what each development can do today, what evidence supports it and what it costs to operate. A prediction score is not a trading return, a faster computer does not repair a weak strategy, and an automated workflow still needs oversight.
| Trend | Practical application | Evidence to demand |
|---|---|---|
| AI and machine learning | Research assistance, forecasts and rule implementation | Chronological evaluation against simpler baselines, after costs |
| Alternative data and NLP | Turn text and other observations into testable features | Point-in-time availability, licensed access and incremental value |
| Low-latency infrastructure | Reduce delays in time-sensitive execution | Measured end-to-end behavior and resilience under load |
| Surveillance and risk controls | Detect unusual activity and constrain system behavior | Coverage tests, investigated alerts and recoverable changes |
| Quantum computing | Explore specialized transformations and models | Task-specific comparisons, replication and deployment costs |
| Cloud and digital-asset infrastructure | Scale research and connect operational workflows | Reliable data, realistic execution and explicit access controls |
AI and Machine Learning: From Predictions to Research Workflows
Different models solve different problems
Deep-learning methods can model sequences or complex relationships, but their usefulness depends on the target and available data. An LSTM may be tested on sequential inputs; a convolutional model may process structured patterns; a language model may help organize research or explain code. These are different tasks, so a single “AI accuracy” number is not a meaningful comparison.
Define the prediction first: next-period direction, volatility, a price range, fill probability or another measurable outcome. Then specify when the inputs become available and how the prediction changes a trading decision. A model that accurately identifies common small moves can still lose money if its errors coincide with large losses or expensive trades.
Begin with a simple reference model and a chronological holdout. Fit preprocessing and feature selection on training data, then apply the learned transformation to later observations. The scikit-learn guidance on data leakage explains why allowing evaluation data into training can produce overly optimistic results.
Generative AI makes implementation more accessible
Coding assistance can shorten the path from a written hypothesis to inspectable code. It can also help explain errors and organize experiment notes. The trader still needs to verify data inputs, calculations, timing and the actual results. A plausible explanation of a backtest is not evidence that the test ran.
Keep research assistance separate from trading authority. Define which tools can read data, which can propose changes and which can submit orders. If execution is connected elsewhere, credentials, position state, order limits and recovery rules need their own controls; generating code does not establish those controls automatically.
Reinforcement learning remains sensitive to the simulator
Reinforcement learning trains a policy around actions and rewards in an environment. It can be investigated for position decisions or execution, but the learned behavior depends on the environment’s assumptions. Unrealistically cheap transactions, unlimited fills or an incomplete penalty for risk can reward behavior that fails outside the simulation.
Evaluate across multiple training runs and unseen periods. Compare with simpler policies, vary transaction costs and inspect turnover, drawdowns and failure cases. Retraining is a change to the system and should be reviewed before deployment; “adaptive” does not mean independently safe or consistently profitable.
Alternative Data: Availability Matters as Much as Variety
News, filings, earnings-call transcripts, online discussions and other observations can add information beyond price and volume. Natural language processing can convert text into event, topic or sentiment features. The value comes from whether those features improve a specific decision after their acquisition and processing costs.
For example, MarketPsych describes analytics across news, filings, transcripts and online posts, with point-in-time entity mapping and sentiment datasets. This is evidence of a data workflow, not a universal forecast accuracy or proof that adding sentiment improves every strategy.
Other potential inputs include shipping activity, satellite observations or aggregated spending data. Before purchasing any dataset, check what population it covers, how it was collected, whether usage is permitted and how historical records are revised. A large dataset can still have selection bias, missing coverage or timestamps that make it unusable for the intended historical test.
Prevent future information from entering the test
Record the time information became available to the strategy, not merely the date of the event it describes. If a report concerns Monday but is released Wednesday, a Monday trade cannot use it. Later corrections and revised labels should not silently replace the versions a trader could actually have seen.
Align event times, release times, ingestion delays and the instrument mapping. Tools such as pandas.merge_asof can match ordered observations backward in time with a tolerance, but the input timestamp must represent genuine availability. A backward join on the wrong timestamp still leaks information.
Test the added dataset against a baseline without it. Hold the evaluation period and execution assumptions constant, and include licensing, storage and processing costs. More features can increase the number of apparently successful experiments without adding durable value.
High-Frequency Trading: Speed Is an Engineering Tradeoff
High-frequency trading is one part of algorithmic trading. A strategy that updates on daily bars does not have the same infrastructure needs as a system competing for short-lived quotes. Match the engineering effort to the decision horizon and the economic consequence of delay.
Time-sensitive systems may use colocated servers, specialized network interfaces, low-latency switches or FPGA processing for particular tasks. Fiber and wireless routes involve different distance, capacity, availability and maintenance considerations. A component’s advertised speed is not the same as the delay from receiving information to obtaining an exchange acknowledgment.
- Measure the whole path: feed arrival, parsing, decision calculation, risk checks, routing and acknowledgments.
- Measure variability: include bursts, congestion, recovery and delayed responses rather than reporting only an average.
- Preserve safeguards: test duplicate prevention, stale-data handling, position limits and a controlled response to uncertain order status.
- Compare economic value: weigh any execution improvement against infrastructure costs and remaining market impact.
For many traders, a realistic fill model and dependable operations matter more than shaving a small amount of processing time. The Alpaca paper-trading documentation illustrates why simulation requires scrutiny: its simulated fills do not constrain order quantity to the quantity available at the best quote. Paper results can therefore differ from executable live capacity.
Execution algorithms also have different objectives. A time schedule distributes an order; a volume benchmark measures another kind of execution target. Neither automatically guarantees full completion, minimal impact or a better price. Test the actual broker implementation and its constraints.
Quantum Computing: A Concrete Experiment, Not a General Speed Guarantee
A useful development to watch is the September 2025 HSBC and IBM research on institutional bond trading. The underlying research paper studies fill-probability estimates: how likely a trade inquiry is to execute at a quoted price. That is more specific than predicting the direction of the whole bond market.
The researchers used production-scale historical trade-event data and an IBM quantum processor to transform inputs for statistical learning. The quantum work was a decoupled offline transformation, with the resulting information used in the modeling workflow. Evaluation included a trade-execution backtest; this was not a demonstration of sending every live order through a quantum computer.
The paper reports improved out-of-sample test scores in its comparisons and suggests that hardware noise contributed to the observed effect. Those findings motivate further study. They do not establish a general advantage over every classical algorithm, a fixed reduction in live execution latency or a guaranteed improvement in trading returns.
Watch for independent replication, stronger classical baselines, performance across different datasets and a full accounting of compute, data and integration costs. The useful milestone is a reproducible improvement in a defined task that remains valuable within the complete workflow.
HSBC’s September 24, 2025 video explains the collaboration from the bank’s perspective. Its headline and improvement claim refer to this experiment; use the paper above to understand the offline design and evaluation limits.
Compliance and Risk Monitoring: Automation Needs Accountability
More automated activity creates a greater need to understand what a system did and why. Pre-trade risk controls constrain orders before submission; operational monitoring tracks whether the system is behaving as intended; surveillance helps identify activity requiring investigation. These functions overlap but are not interchangeable.
The Eventus Validus platform describes surveillance procedures, investigative tools, risk checks and algorithm monitoring. Vendor throughput and alert-automation statistics describe particular capabilities or reported operating results. They should not be treated as proof of complete abuse detection or automatic compliance.
| Control | Purpose | What to test |
|---|---|---|
| Order and exposure limits | Constrain proposed activity | Oversized, duplicate and unexpectedly repeated orders |
| Data and connection checks | Detect unreliable inputs or uncertain state | Stale feeds, disconnects and delayed acknowledgments |
| Pause and recovery procedures | Stop new activity and restore known state | Whether existing positions and open orders remain after a pause |
| Surveillance and investigation | Review potentially problematic patterns | Alert coverage, missed cases and documented resolution |
| Change management | Make releases traceable and recoverable | Version records, approvals where required and rollback behavior |
FINRA’s 2015 guidance for member firms discusses testing, change management and supervision of algorithmic strategies. It is a useful example of established operational expectations for its stated audience, rather than a certification that a retail tool complies with every jurisdiction’s rules.
Risk estimates also have limits. Value at Risk depends on a model and horizon; Monte Carlo outcomes depend on the scenarios and assumptions supplied. Neither promises that losses will remain within the estimate. Stops can help define an exit process, but their eventual execution price may differ from the trigger price, and limit conditions can leave orders unfilled.
A useful trend is making monitoring more actionable: fewer poorly targeted alerts, clearer ownership and records that support investigation. Reducing alert volume alone is not success if important cases are missed. Evaluate both detection quality and the human process for resolving exceptions.
Cloud and Digital-Asset Workflows: Scale Without Losing Control
Cloud infrastructure can make storage, research environments and parallel experiments easier to provision. It also introduces decisions about service availability, data location, access permissions, cost and reproducibility. Record dependencies, data versions and experiment settings so results can be reproduced after an environment changes.
Separate the research environment from execution where their requirements differ. A long-running model-training job should not accidentally interfere with order monitoring. Test what happens when a service is unavailable, a quota is exhausted or a credential expires; a hosted system still needs an operational owner.
Digital-asset and decentralized-finance workflows add different execution considerations, including transaction fees, transaction ordering, settlement delays and the behavior of the chosen venue or protocol. A chart price does not establish the price at which a transaction will settle. Assess wallet permissions, contract exposure and recovery procedures before connecting execution.
These developments broaden the available tools, but availability is not proof that a particular trader needs them. Adopt a service when it solves a measured bottleneck and its operational requirements are understood.
Put These Trends to Work with LuxAlgo
Start in LuxAlgo’s native charts with a specific market question. Confirm the instrument, timeframe, session and documented data coverage. A chart workflow is a practical place to investigate a price-based hypothesis; it should not be assumed to contain a separately licensed sentiment feed, satellite dataset or executable order book.
Use Quant, our coding agent to turn a clear strategy specification into code. Inspect the generated code and run it yourself. Explain the entry, exit, sizing, completed-bar timing and cost assumptions, and ask for missing inputs to be identified rather than invented.
Example prompt: “Implement this chart-based hypothesis using the available data. Explain when each input becomes known, include configurable trading costs and keep the rules inspectable. Identify any unavailable external data. I will review the code, run the strategy and compare the result with a simpler baseline.”
Use native strategy testing on standard candles with separate development and evaluation periods. Change one hypothesis at a time and retain unsuccessful experiments as well as favorable ones. A larger search increases the need to account for selection and overfitting.
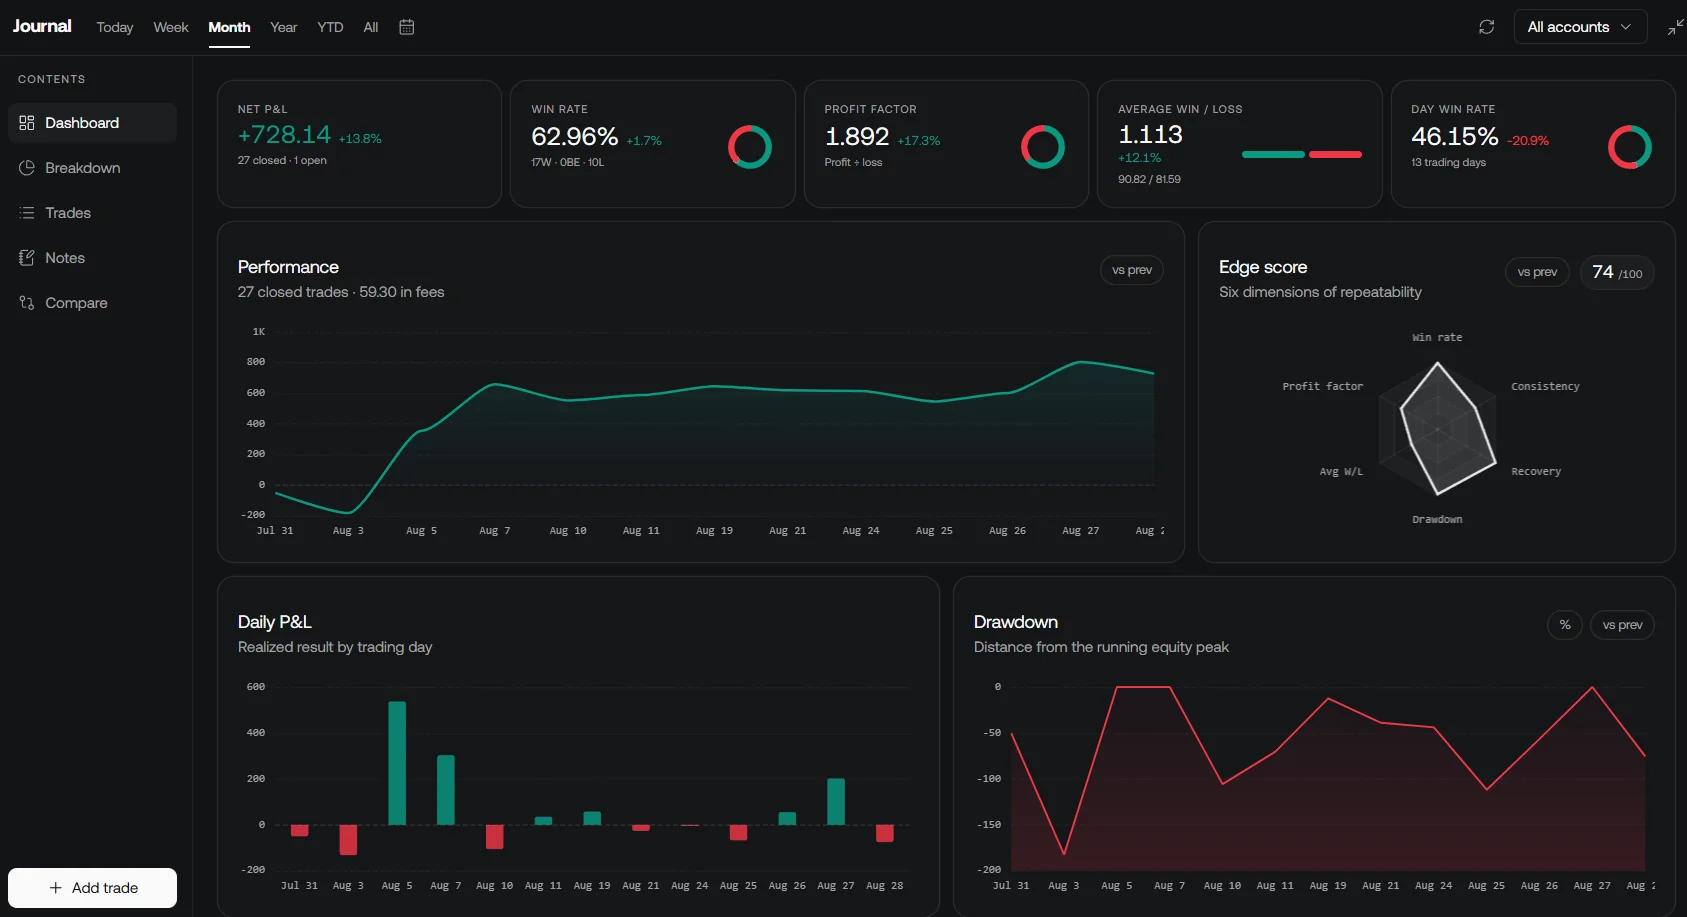
Review compatible recorded trades in the native LuxAlgo journal alongside your research notes and broker records. Compare what the rules signaled with actual fills and costs where those records are available. This helps separate a modeling problem from an execution problem.
What to Watch Next
- Better evaluation: results that disclose data timing, baselines, costs and unsuccessful experiments.
- Useful AI assistance: inspectable implementations and reproducible analysis with clear human review.
- Reliable data: point-in-time histories, transparent coverage and evidence that new inputs add value.
- Operational improvements: clearer order state, tested recovery and accountable monitoring.
- Emerging research: replicated quantum or other specialized results that remain useful after full integration costs.
The strongest way to prepare is to build a repeatable process: define the question, verify the data, implement the rule, test it under realistic assumptions and review actual outcomes. That process makes it easier to adopt a useful new tool without mistaking an impressive demonstration for a dependable trading edge.
Frequently Asked Questions
Will AI replace every trading decision?
AI can assist research, coding and modeling, but useful deployment still requires verified inputs, realistic evaluation and accountable control of execution. A generated prediction or strategy is not proof of a profitable trade.
Does quantum computing already make live trading faster?
The HSBC and IBM study discussed here used an offline quantum transformation and backtested fill-probability models. It does not establish a general live-execution speed advantage or guaranteed trading profits.
Is alternative data always better than price data?
No. It needs timely, permitted access and evidence of incremental value after acquisition and processing costs. Incorrect availability timestamps can create misleading backtest results.
Do retail strategies need high-frequency infrastructure?
Not necessarily. Infrastructure should match the strategy horizon and execution requirements. Reliable data, realistic costs and recovery procedures may matter more than reducing a small processing delay.
Can Quant automatically validate a trading idea?
Quant, our coding agent, can help implement a defined strategy. You should inspect the generated code, run it yourself and evaluate the actual results with appropriate data, costs and separate test periods.
Read next