Backtest Everything.
Every strategy Quant builds can be proven against history in the same window it was built in: next-gen, bias-free, and refinable in plain language.
Free to start. No credit card required.
From idea to evidence.
The old loop was fragmented: build in one tool, restructure the code by hand, test somewhere else. On Quant it's one window: describe, chart, backtest, refine, then save, and the next refinement picks up exactly where this one ended.
01Describe
Plain-language logic
02Chart
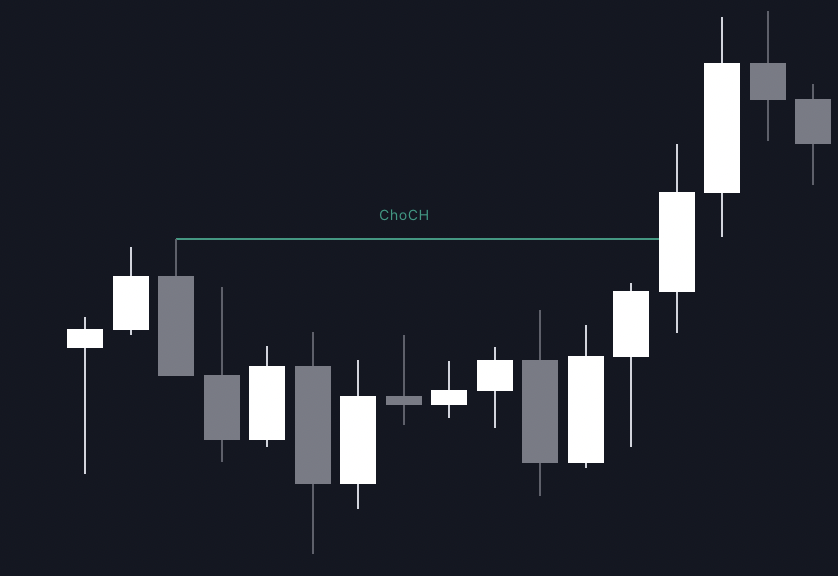
Rendered as you talk
03Backtest
Net+161,073.60 USDT
Proven against history
04Refine
Iterated in conversation
05Save
New Overflow
BTCUSDT · 1h
The next pass starts here
Read the whole report.
A single headline number isn't a verdict. The report shows you quality.
Net profit, profit factor, win rate, average P&L, and closed trades, split by long and short, so you see whether a strategy only works in one direction. Daily P&L, weekday performance, and trade distribution get their own visual breakdowns, with Monte Carlo when you want to go deeper. Strong strategies show you where they're strong; weak ones show you exactly what to fix next.
Research that compounds.
Strategy development is never one attempt. Save every strategy inside Quant, return to it from the sidebar, and build variations without screenshots, pasted code, or scattered notes. Your research becomes a collection, and the ideas that showed promise stay one click from their next refinement.
Saved Strategies


EURUSD
EUR/USD

AUDUSD
AUD/USD
CRWD
CrowdStrike Holdings, Inc.
ZS
Soybean Futures

SPY
SPDR S&P 500 ETF TRUST
BTCUSDT
Bitcoin
NQ
E-mini NASDAQ 100 Futures
Variations
New Overflow · HyperWave Below 50
BTCUSDT · 1h · saved in Quant
Baseline HyperWave conditions
PF 1.41Net +38,204
+ Overflow threshold below 50
PF 1.92Net +96,510
+ Symmetric long / short exits
PF 2.333Net +161,073current
Take it to TradingView®. If you want.
Nothing on this page requires leaving LuxAlgo. Porting is pure optionality. Quant writes Pine Script®, so the generated code can be pasted onto a TradingView® chart, and strategies you find in the Strategy Screener can travel the same way.
// Exported from Quant: Overflow + HyperWave modules inline//@version=6strategy("New Overflow · HyperWave Below 50", initial_capital = 100000)longEntry = newBearishOverflow and moneyflow < 50shortEntry = newBullishOverflow and moneyflow > 50if longEntrystrategy.entry("Long", strategy.long)if shortEntrystrategy.entry("Short", strategy.short)
Strategies you find in the Strategy Screener can be taken to a TradingView® chart as well, by choice. Everything on this page runs natively on LuxAlgo first.
As Quant's engine grows, some strategies may be too advanced for Pine Script®, but most convert cleanly
Frequent questions.
Yes. Any strategy Quant builds can be backtested without leaving the conversation. The full performance report returns in the same window you built it in.
Prove it first.
Build it, test it, trust it, before a dollar is on the line. Jump in free.