Ken Griffin: Market Tactics Explained
Ken Griffin’s public investment framework emphasizes research, technology, specialist teams and disciplined portfolio risk management. Citadel applies those resources across multiple investment strategies. There is no single public algorithm, fixed position-size rule or market-neutral formula that reproduces the firm’s results.
The useful lessons concern how a trading decision is researched, sized, tested and reviewed. Start by distinguishing Citadel’s investment-management business from Citadel Securities’ market-making business, then separate a strategy’s objective from a promise about its performance.
Citadel and Citadel Securities Have Different Roles
Citadel’s investment overview identifies five major areas: Commodities, Credit & Convertibles, Equities, Fixed Income & Macro, and Global Quantitative Strategies. Each requires its own research and risk analysis. Describing the whole firm as one automated, near-zero-exposure trading system misses those differences.
Citadel Securities describes its role in providing liquidity through trading, research and technology. Market-making activity, quoted trading volumes and infrastructure statements about that business should not be used as if they describe a Citadel investment fund.
The distinction also matters when interpreting financial figures. Assets under management measure capital managed at a specified date; they are not the compounded value of one unchanged initial investment. Aggregate investor gains, a fund’s percentage return and a market maker’s trading volume are different measures. Compare the entity, period and definition before drawing a conclusion.
| Measure or activity | What it describes | Common mistake |
|---|---|---|
| Assets under management | Capital managed under the stated scope at a date | Treating growth in assets as one investor’s compounded return |
| Fund return | Performance of a particular fund over a stated period | Applying it to all funds or to the management company |
| Aggregate investor gains | An absolute monetary result under the source’s methodology | Treating it as an annualized percentage return |
| Market-making volume | Trading activity in a liquidity-provision business | Calling it hedge-fund assets or investment profit |
Griffin on Distributed Decision-Making
This retained interview clip from David Rubenstein’s channel was published March 22, 2022, and recorded in Chicago on February 25. Griffin discusses distributed decision-making and the organization behind Citadel. It provides his perspective on the firm, rather than a complete trading system or current performance report.
Research and Technology Work at Different Levels
Citadel’s equities description emphasizes deep fundamental research, financial analysis, data and portfolio construction. Its engineers and quantitative researchers support investment teams with tools, analysis and risk information. That is different from saying every investment decision is made automatically.
Its Global Quantitative Strategies team, formed in late 2012, describes a fully automated trading strategy across geographies, asset classes and investment horizons. Researchers and engineers collaborate from idea generation through portfolio construction and execution. Automated trading still depends on human decisions about research, models, implementation and oversight.
A concrete example in the investment overview comes from commodities. Citadel describes atmospheric scientists working with high-performance computing specialists to turn weather data into forecasts relevant to markets such as natural gas and agricultural products. The lesson is to connect a dataset to an economic mechanism—not merely to collect more data.
| Research stage | Question to answer | Practical check |
|---|---|---|
| Hypothesis | Why might this observation relate to a future outcome? | State the mechanism and what would contradict it |
| Data | Was this information available when the decision would be made? | Check timestamps, coverage, revisions and missing observations |
| Implementation | Does the model express the intended rule? | Inspect the code and individual decisions |
| Portfolio construction | How do positions interact? | Measure shared exposures, gross size and plausible losses |
| Execution and review | Can the assumed trade occur at the modeled cost? | Compare actual or realistic fills with the test assumptions |
A mathematically sophisticated model can still use flawed data, overfit a sample or behave differently after market conditions change. Technology improves the ability to investigate and act; it does not establish that a detected relationship will remain profitable.
Independent Risk Oversight Is Part of the Process
Citadel says its Portfolio Construction and Risk Group operates independently of the investment team and reports directly to the CEO. Its responsibilities include identifying exposures and performance drivers, monitoring risk tolerance and maintaining analytical tools. The firm describes constant monitoring, review, automated testing and updated stress scenarios.
These controls should not be rewritten as a guarantee that the system automatically removes every dangerous position. Citadel’s own risk disclosure says losses can occur despite its protocols, including from risks that are not monitored or are larger than forecast. A dashboard cannot eliminate uncertainty or force liquidity to remain available.
For an individual research process, the transferable idea is to review risk separately from the enthusiasm behind a trade. Ask what happens if the thesis is wrong, if several positions move together, or if exiting becomes more expensive than expected. Record those answers before focusing on the potential gain.
Stress Tests Should Include Execution and Funding
| Scenario | Exposure to examine | Why it matters |
|---|---|---|
| Broad market shock | Market sensitivity and correlated positions | Several apparently different trades can lose together |
| Company-specific gap | Single-name and event exposure | An exit may occur far beyond the planned price |
| Liquidity deterioration | Position size relative to executable liquidity | Historical average volume does not guarantee an orderly exit |
| Financing pressure | Margin needs and funding availability | A position can require cash before a thesis has time to develop |
| Relationship breakdown | Long-short hedges and estimated correlations | An assumed offset can weaken or reverse |
Stress testing is a way to expose assumptions, not to prove the maximum possible loss. Include scenarios beyond the best-fitting historical period and consider whether several adverse changes could happen at once. Revisit the scenarios when instruments, leverage or market conditions change.
Market-Neutral Does Not Mean Risk-Free
Citadel describes its equities approach as market-neutral. This is an investment objective focused on reducing exposure to broad market direction while seeking returns from other sources. It should not be generalized into a claim that every strategy in the firm has zero market exposure or produces gains in every market.
Equal long and short dollar amounts create dollar neutrality under the chosen measurement. They do not necessarily create beta neutrality, sector neutrality or protection from a liquidity shock. Beta is an estimate of sensitivity to a market benchmark, and that estimate can change.
Consider a hypothetical portfolio with a $100,000 long position and a $100,000 short position. Gross dollar exposure is $200,000 and net dollar exposure is zero. If the long position has an estimated beta of 1.5 and the short position has a beta of 0.8, the simplified net beta-weighted dollar exposure is $70,000: $100,000 × 1.5 − $100,000 × 0.8.
Even that calculation is only as useful as the estimates and benchmark. It does not capture every risk. The long could fall 10% while the shorted stock rises 10%, producing a combined $20,000 loss before costs. Opposing position directions alone do not make the portfolio safe.
Nor is there a general rule that short positions contribute more profit than long positions. The result depends on security selection, sizing, timing and costs. A short position also introduces risks and practical requirements that are different from simply selling an owned holding.
Position Exposure and Planned Risk Are Different
A statement such as “use 1% per trade” is ambiguous unless it says whether 1% refers to the position’s value or a planned loss. It should not be attributed to Griffin as a universal rule without a direct source.
For a hypothetical $100,000 account, 1% planned risk is $1,000. Buying a stock at $50 with an intended exit at $48 gives a $2 per-share planned price loss. Dividing $1,000 by $2 gives 500 shares, worth $25,000 at entry. That is 25% position exposure, not 1%, before considering fees or other constraints.
This arithmetic is a sizing illustration, not a recommended allocation or a guaranteed loss cap. If an adverse gap leads to an exit at $45, the price loss on 500 shares is $2,500. Check liquidity, account limits and the interaction with other positions before deciding whether a calculated size is appropriate.
Investor.gov’s order-type guide explains that a stock stop order becomes a market order when triggered; its execution price is not guaranteed. A stop-limit order can remain unfilled. An order instruction cannot remove the risks of a gap or trading interruption.
Use LuxAlgo to Test a Defined Market Question
In LuxAlgo’s native charts, begin with a specific, observable hypothesis. Compare the relevant symbols and timeframes, record the data source, and explain why the condition might matter. This is a workflow for your own research; it does not imply Griffin or Citadel uses LuxAlgo or that a chart test replicates an institutional platform.
Review native data coverage before interpreting results. The documented US-equity source is Cboe EDGX rather than a consolidated all-venue feed. A candle series does not reproduce a market maker’s queue position, an institution’s full portfolio or its proprietary weather research.
Ask Quant, our coding agent to help express a supported chart-strategy hypothesis. Inspect the generated code and run it manually. Then review settings, costs and individual trades before comparing another sample. Test a later period and avoid selecting only the version that best fits the original data.
The workspace demonstration below shows how to organize related chart experiments. Keep the market, timeframe, rule version and cost assumptions in your research records so a result remains understandable when you return to it.
Review Decisions and Execution Together
A useful review compares the expected behavior with the actual outcome. Examine drawdowns, costs, average gains and losses, and whether results depend on a narrow market condition. A favorable backtest or a small group of profitable trades does not prove that a strategy will scale.
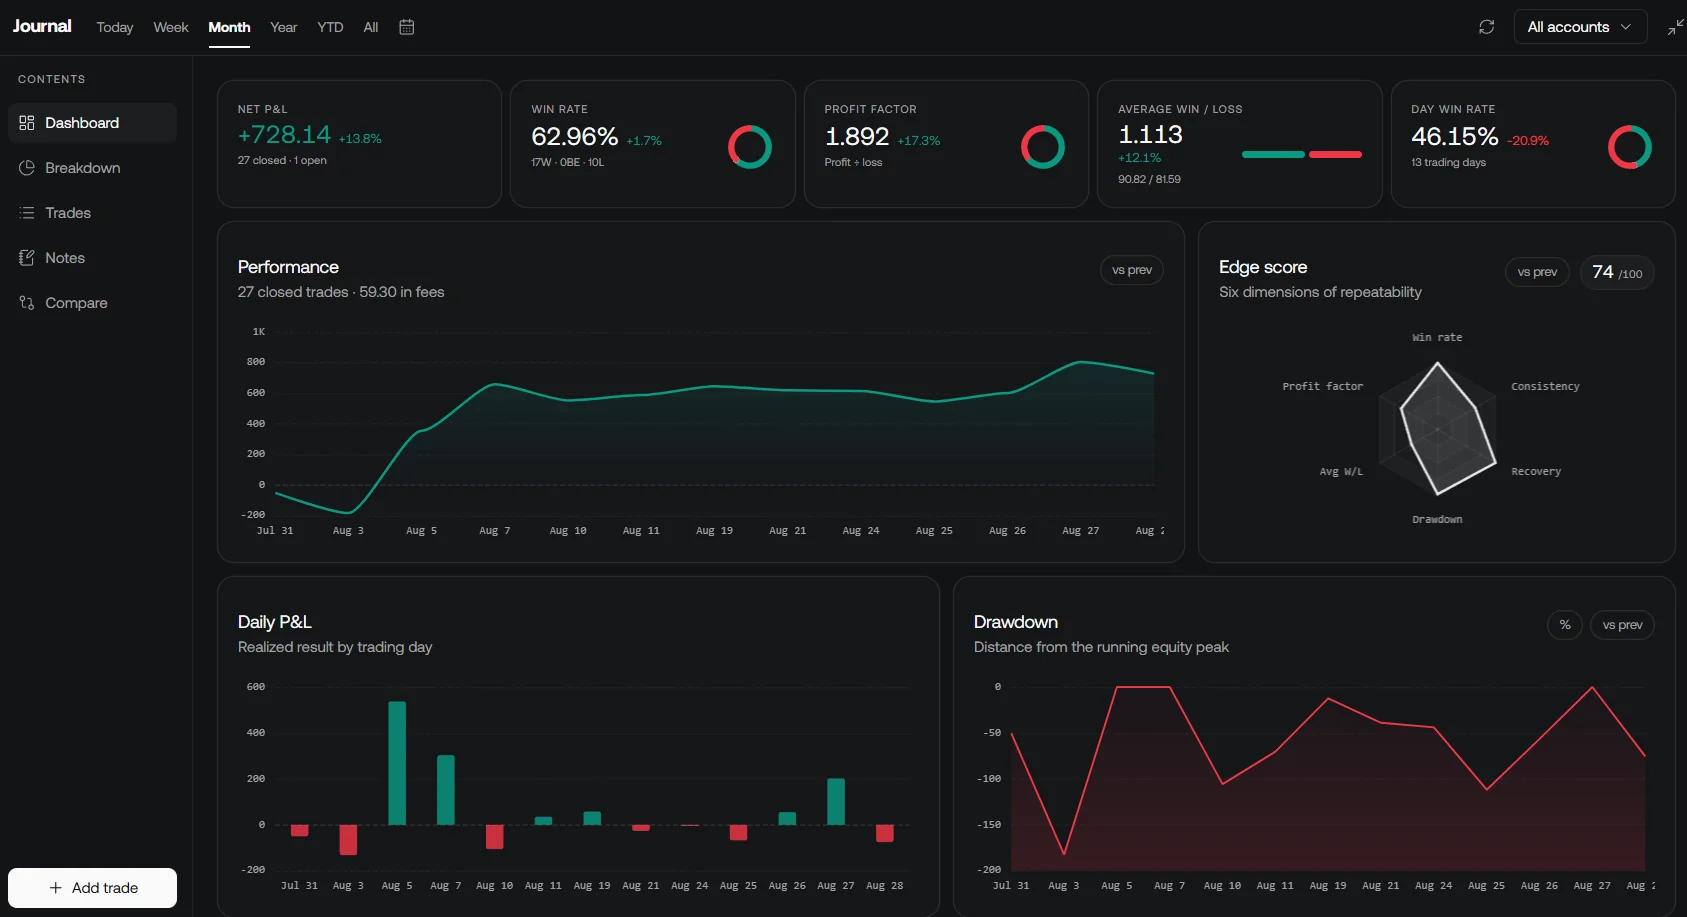
The native journal supports reviewing imported trade records. Compare those records with broker statements and the original plan. Keep trading performance separate from deposits, withdrawals or a change in account size when assessing improvement.
- Write a falsifiable hypothesis before testing or entering a position.
- Check whether the source describes Citadel, a particular investment strategy or Citadel Securities.
- Separate gross exposure, net exposure and planned loss.
- Stress-test imperfect hedges, gaps, liquidity and financing needs.
- Review generated code, execution assumptions and an unused test period.
- Use actual trade records to investigate differences from the plan.
The strongest lesson from Griffin’s public framework is disciplined research supported by clear accountability. Adopting that discipline can improve how you investigate a trade; it does not give access to a proprietary strategy or guarantee the same outcome.
Frequently Asked Questions
Are Citadel and Citadel Securities the same business?
They have different roles. Citadel’s investment-management business runs multiple investment strategies; Citadel Securities provides liquidity through its market-making activities. Their metrics and operating descriptions should not be mixed.
Does Citadel use only fully automated trading?
No. Its public materials describe fundamental equity research as well as the fully automated Global Quantitative Strategies approach. One strategy’s description does not establish how every investment in the firm is made.
Do equal long and short dollar amounts eliminate market risk?
No. They create dollar neutrality under that calculation, but different market sensitivities and other exposures can remain. Both legs can also lose at the same time.
Is risking 1% the same as investing 1% of the account?
No. Planned risk depends on position size and the assumed adverse price move. A much larger position can have a planned 1% loss, and gaps or costs can make the actual loss larger.
Can LuxAlgo reproduce Citadel’s institutional strategy?
No. Native charts and Quant can support defined chart research, but they do not reproduce proprietary datasets, market-making execution or an institution’s full risk platform. Inspect generated code and run supported tests manually.
Read next