Steven Cohen: Methods & Tactics Uncovered
Steven Cohen’s career offers lessons in research, risk control, and adapting when an investment thesis changes. Those lessons are more useful than trying to copy a supposed secret indicator or a fixed trading schedule. His firm combines different investment styles, so it is misleading to describe every decision as high-frequency trading.
Point72’s biography records Cohen’s founding of SAC Capital in 1992, the transition to a family office in 2014, and the return to managing outside capital in 2018. Historical results from different funds, periods, and fee structures should not be treated as one repeatable annual return.
Below, we separate documented firm practices from illustrative techniques an individual trader can study. LuxAlgo’s native charts and Quant, our coding agent, support the technical research; they do not reproduce Point72’s proprietary information, portfolio, or execution infrastructure.
Steve Cohen on building an investing career
In this Point72 interview, Cohen and Harry Schwefel discuss investment talent, idea generation, and development. It provides first-hand context for the importance of a repeatable research process rather than a mechanical entry recipe.
Data-driven trading starts with a specific question
Point72’s investment-strategy overview distinguishes fundamental equities, systematic investing through Cubist, and discretionary global macro. These approaches have different research inputs and holding periods. Computer-driven investing does not automatically mean every strategy competes on millisecond speed.
The firm’s fundamental-equities research description explains that its Market Intelligence team combines company research with machine learning, macro and sell-side research, and quantitative methods. For an individual trader, the practical lesson is to make different evidence sources answer a defined question.
| Research input | Useful question | Check before acting |
|---|---|---|
| Company results and filings | What changed in earnings, cash flow, or the business outlook? | Publication time, accounting adjustments, and what was already expected |
| Economic releases | Does the change affect the investment thesis? | Revisions, release timing, and exposure to the same economic driver |
| Price and volume | How is the market responding? | Venue, session, liquidity, and whether the bar has closed |
| Alternative data | Does an additional dataset improve the forecast? | Lawful sourcing, licensing, sample bias, and out-of-sample usefulness |
Combine fundamental research with chart evidence
A company can report higher sales while its share price falls because investors expected more. Conversely, a price rally does not establish that the business is improving. Record the thesis, the evidence against it, the expected catalyst, and the time horizon before choosing an entry.
For an earnings study involving a company such as Equinix, distinguish the announcement’s actual figures from the market’s prior expectations. Then measure the price response over a specified window. A selected price jump does not establish Cohen’s entry, position size, or realized profit.
Historical example: check the Ardea deal’s scale
AstraZeneca’s April 2012 announcement valued its proposed Ardea acquisition at $32 per share, approximately $1.26 billion including existing cash. The announced price represented a 54% premium to the preceding trading day’s close. That is the transaction’s valuation and price comparison, not evidence of a $26.7 billion Cohen position or a $40 billion outcome.
The research lesson is to reconcile units and dates before building a narrative. Company value, a fund’s disclosed holding, purchase cost, and trading profit are different quantities. An acquisition announcement also does not reveal the investor’s earlier reasoning.
Execution speed matters only after the decision is sound
Fast processing can help a team respond to information, but more trades are not inherently better. A strategy must overcome spreads, fees, adverse execution, and the possibility that an apparent opportunity disappears before an order fills.
Suppose a model estimates a gross advantage of $0.08 per share, while expected round-trip spread, fees, and slippage total $0.06. The estimated net advantage is $0.02. If costs rise to $0.10, the same forecast implies a $0.02 loss per share. These are assumptions to test, not Cohen’s results.
A candle backtest cannot establish queue position or subsecond execution quality. Match the simulation to the strategy’s actual decision frequency and data resolution. Start with reproducible rules rather than assuming that faster automation creates an advantage.
Risk management: size the trade and the portfolio
Liquidity, leverage, and concentration interact. A position that looks manageable in normal trading can become difficult to exit after an earnings surprise or market disruption. The following examples illustrate general risk analysis; they are not published Point72 limits.
Position sizing in cash terms
Assume a $40 stock entry, a planned $38 exit threshold, and a chosen $200 risk budget. The $2 distance implies 100 shares before costs, or $4,000 of position value. If the stock gaps and the actual sale is $35, the loss becomes $500 before fees. The planned $200 is not a maximum-loss guarantee.
Investor.gov’s order explanation distinguishes stop-market execution from stop-limit price restrictions: the former can fill beyond the trigger, while the latter can remain unfilled. Choose the order behavior deliberately.
Gross and net exposure answer different questions
| Illustrative portfolio | Calculation | Meaning |
|---|---|---|
| $10,000 account equity; $12,000 long and $8,000 short | Gross exposure: ($12,000 + $8,000) ÷ $10,000 = 200% | Total absolute position exposure is twice equity |
| Same positions | Net exposure: ($12,000 − $8,000) ÷ $10,000 = 40% | Dollar exposure is tilted long |
| Long holdings fall 10%; short holdings rise 10% | −$1,200 − $800 = −$2,000 | A 20% equity loss before financing and other costs |
A low net figure does not mean low risk. Different securities can move against both sides, and sector concentration may remain despite several ticker symbols. Dollar net exposure also differs from beta-adjusted exposure. Short positions bring borrow availability, financing, and potentially unlimited loss; this example is not a suggested portfolio.
Define exits before the market forces a decision
Write separate responses for a price-based exit, a broken business thesis, a missed catalyst, and excessive combined exposure. “Buy after stabilization” or “short at the peak” is too vague to test. Specify observable conditions and when they must be confirmed, without using future bars to identify the entry retrospectively.
Market intelligence and expert research
Industry specialists can help explain supply chains, customer behavior, or business economics. Their comments still need corroboration and an appropriate information boundary. Build research from lawfully obtained information; access to a knowledgeable person does not make confidential material nonpublic information appropriate to trade on.
For an alternative dataset, ask who is represented, who is missing, when observations become available, and whether the collection method changed. A historical relationship can disappear after publication or after the trading costs of exploiting it are included.
Quantopian is a historical example, not an active funding promise
The original Quantopian fund and community trading platform closed in 2020. QuantRocket documents the continuing availability of its open-source tools and educational materials. Do not confuse the survival of that software with continued access to the former capital-allocation program.
The enduring question for a crowdsourced model is whether it adds useful performance after costs on data that were not used to select it. Community size, algorithm complexity, and a large capital commitment do not answer that question.
Build a research workflow in LuxAlgo
Use LuxAlgo’s native charts to compare a candidate with a relevant benchmark and examine more than one timeframe. Mark the proposed entry and exit conditions before reviewing later prices.
Ask Quant to implement a clearly specified technical hypothesis. For example, define a completed-bar trend condition, an entry trigger, a fixed position size, and an exit rule. Treat the output as a draft to inspect in Code, then Run it over the chart’s history.
Review the backtest and Trades log. Set commission, slippage, capital, and order size in Properties, and examine losing trades as well as headline performance. Keep a separate evaluation period and record each rule change. A successful run establishes that the script executed; it does not establish a durable investment edge.
Check the data source and session. Native US equity data comes from Cboe EDGX, so its activity is venue-specific. Footprints summarize executed volume at price on supported markets; they are not a live order book. Chart research also does not automatically incorporate point-in-time company fundamentals or reproduce a multi-manager portfolio.
Choose tools by the task they support
LuxAlgo is a useful starting point when the task is to turn a technical idea into code, inspect it on native charts, and review the resulting trades. Other platforms serve related workflows:
- TrendSpider offers market scanning and a Strategy Tester for constructing and assessing rules.
- Trade Ideas’ Holly presents strategy ideas and trade-management interfaces. Evaluate its assumptions and actual costs instead of treating a quoted win rate as a promised result.
- TradingView provides charting and Pine Script® tools for custom studies. Data access and features depend on the selected services.
No platform choice establishes that a strategy follows Cohen’s proprietary methods. Likewise, a stock-market approach needs fresh testing before transfer to futures, forex, or crypto, where sessions, contract values, financing, and liquidity differ.
Trading psychology: review the process as well as the outcome
Point72’s recap of Cohen’s 2025 Sohn conversation emphasizes preparation, adapting to conditions, and maintaining a process through difficult periods. These are useful review habits, not a guarantee that discipline prevents losses.
After a trade, distinguish a reasonable decision that lost from a rule violation that happened to win. Record the evidence available at entry, what changed, actual execution costs, and whether the position fit the planned exposure.
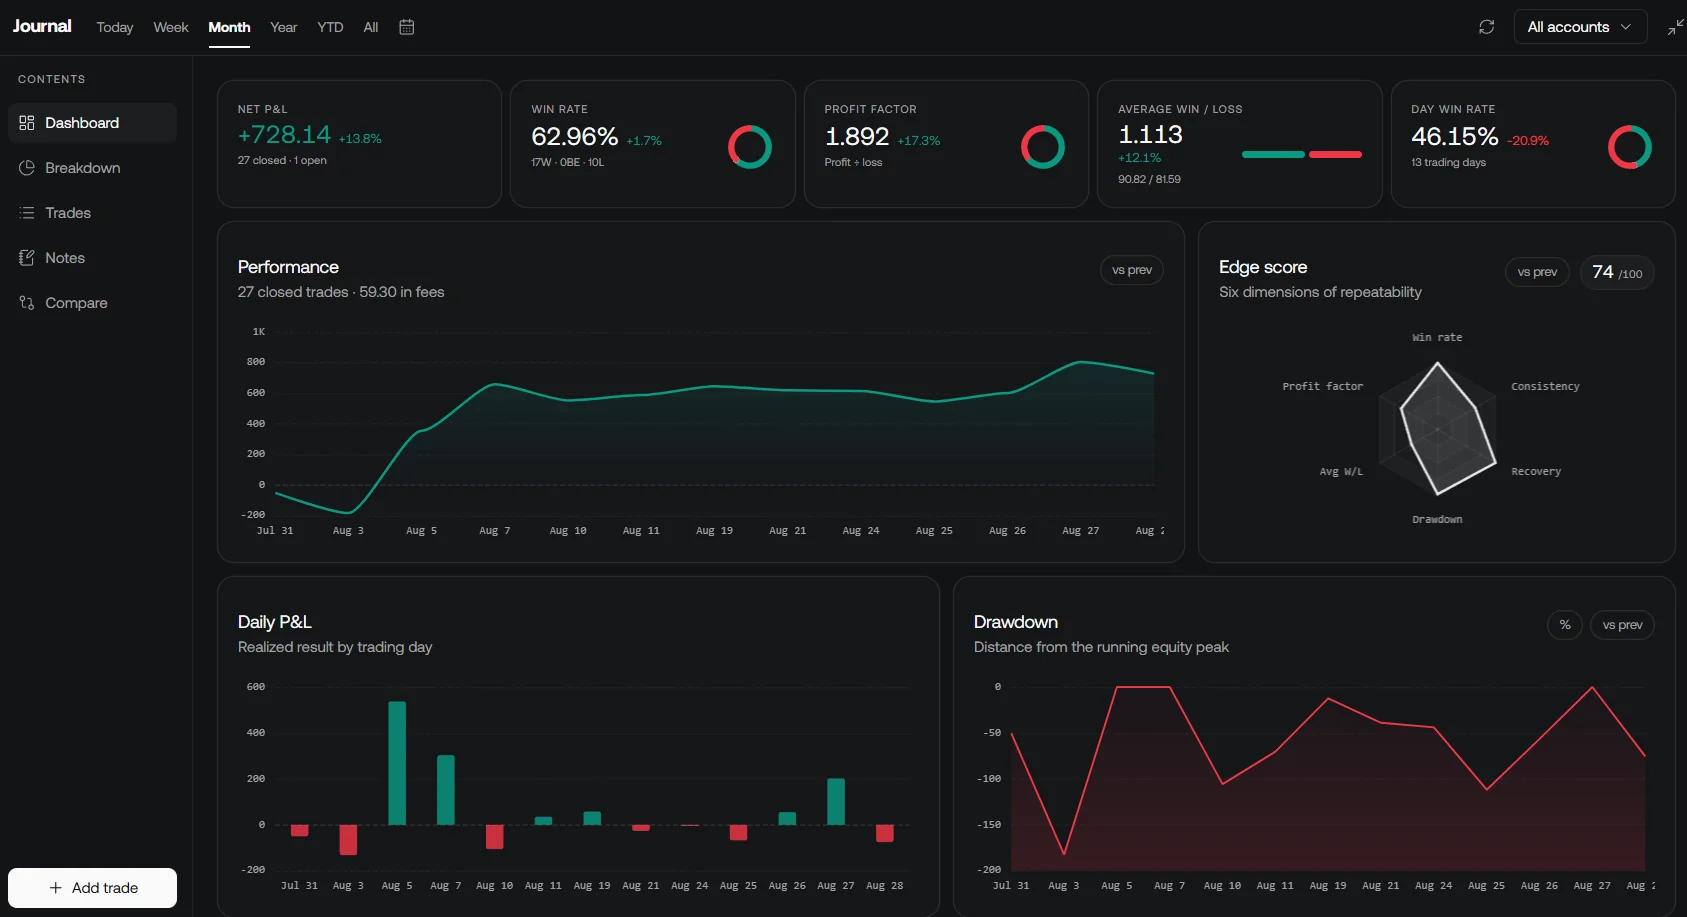
Open the LuxAlgo Journal from the workspace header. Add fills manually, import a statement, or use a supported broker connection, then review trades and notes. The record supports reflection; it does not automatically determine whether the original thesis was sound or prevent an impulsive order.
The most practical takeaway from studying Cohen is to make research, exposure, execution, and review work together. Start with evidence, state the conditions that would change your view, and judge the process across a representative set of outcomes.
Read next