Backtesting vs. Forward Testing: Validating Your Strategy
Backtesting evaluates a strategy on historical data. Live forward testing records how a fixed strategy behaves as new market data arrives. Use both to investigate an idea, check its assumptions, and uncover practical problems. Neither method proves that future trading will be profitable.
There is an important terminology difference: some platforms call a later, reserved portion of historical data a “forward test.” That is an out-of-sample historical test, distinct from running a paper account in real time. Before comparing results, establish which meaning is being used.
| Method | What it uses | What it helps assess | Main limitation |
|---|---|---|---|
| Development backtest | Historical data used to build the rules | Implementation, initial plausibility, and sensitivity | Results are influenced by the choices made during development |
| Historical out-of-sample test | Reserved historical data | Performance beyond the development sample | Repeated inspection can contaminate the test |
| Live paper forward test | New data and simulated orders | Signal behavior, operational workflow, and current conditions | Simulated fills and emotions differ from real trading |
Backtests can run quickly; live observation advances at market speed. Neither simulated method places real capital into its hypothetical trades, although data, software, and time can cost money. A small real-money forward test is a separate activity with actual loss risk.
How to build a useful backtest
Define the decision before writing the code
Specify the instrument and venue, timeframe, session, entry condition, exit rules, position sizing, and whether decisions use completed bars. State how simultaneous signals, gaps, and overlapping positions should be handled.
For example, “buy when momentum improves” is ambiguous. “Enter after a completed bar closes above the prior 20-bar high, excluding the current bar from that high” is testable. It still needs order timing, size, and exits before it becomes a complete strategy.
Check the data and simulation assumptions
- Timing: use information only after it was available. Financial results belong at their publication time, not automatically at the accounting period’s end.
- Universe: include historical constituents and delisted securities when the strategy’s scope requires them.
- Price history: understand missing bars, splits, dividends, futures rolls, and venue or session differences.
- Execution: model fees, spread, slippage, financing, and borrow costs where relevant. Avoid counting the same cost twice.
- Intrabar behavior: a candle that reaches both a stop and target does not, by itself, reveal which happened first.
QuantConnect’s research guide explains why release dates and historical membership matter: using later knowledge can make an otherwise ordinary strategy look unusually successful. A clean-looking equity curve cannot reveal whether those inputs were valid.
Choose a history length that fits the strategy’s frequency and market. Twenty years is not a universal requirement or a guarantee of quality. A long series may include obsolete market structure; a short series may miss conditions that matter. Record the periods and conditions actually covered.
Protect the test from repeated tuning
Overfitting occurs when choices are shaped too closely around the sample’s noise. Trying more indicators, assets, thresholds, and exit variations creates more opportunities to find a lucky historical result.
Keep a development log that includes rejected variants. The research paper The Probability of Backtest Overfitting explains why a simple holdout does not fully account for repeated strategy selection or prior knowledge of historical markets. Reserving data is useful, but it does not make the entire research process unbiased.
A chronological testing sequence
- Develop: build and debug the hypothesis on an earlier period.
- Validate: compare a limited set of planned choices on a later period. Record every comparison.
- Freeze: save the final code, parameters, data definition, costs, and evaluation criteria.
- Evaluate: run the frozen version on a reserved final period, then observe it prospectively in paper trading.
If you change the rules after seeing the final period, that period has become development evidence. Label the new version honestly and obtain new evaluation evidence. Do not silently reuse the same “unseen” period until a result looks good.
Walk-forward testing repeats a predefined train-then-test schedule across time. Select the window lengths and retraining process before judging the resulting test segments. Choosing the best schedule after comparing many schedules introduces another layer of selection.
Run the technical backtest in LuxAlgo
Use Quant, our coding agent, to turn a defined technical hypothesis into a strategy on LuxAlgo’s native charts. Describe the entry, exit, sizing, and risk rules, then inspect the generated script in Code and click Run.
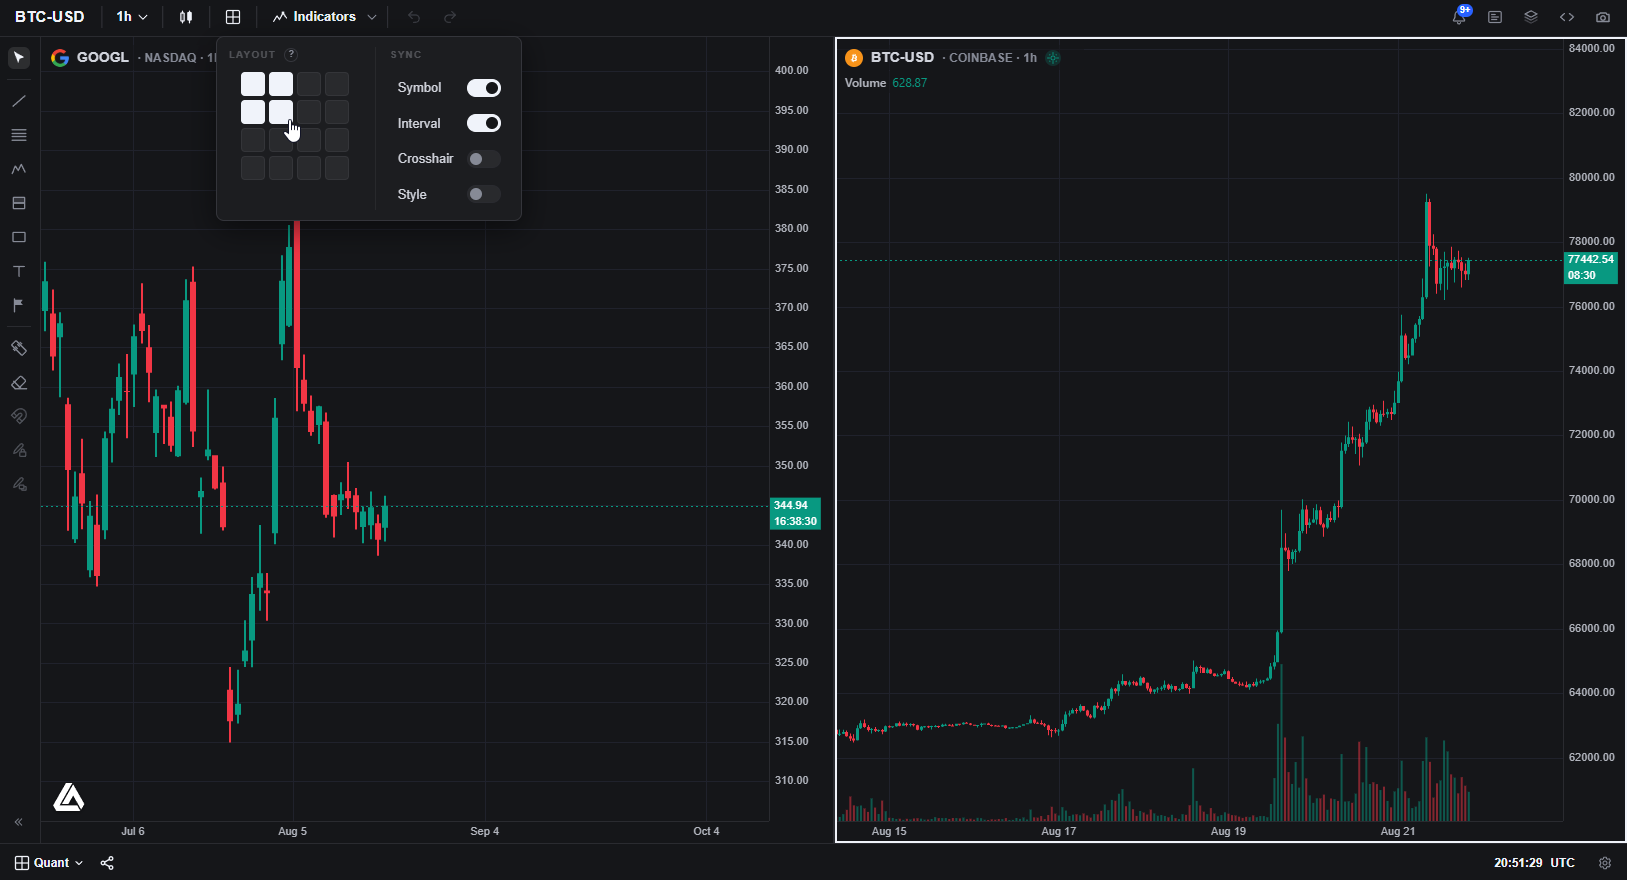
Use Inputs for script parameters and Properties for simulation assumptions such as initial capital, order size, pyramiding, commission, slippage, and margin. Code that runs without errors can still implement the wrong rule or use unsuitable assumptions.
The backtest viewer provides Performance, Trades Analysis, and Trades Log views. Inspect individual entries and exits, the long/short split, and whether a few unusually large winners dominate the result. Use standard price candles: synthetic Heikin Ashi prices are not prices you can necessarily trade.
Check LuxAlgo’s market-data coverage and history limits. Available history is measured in bars by plan, so a lower timeframe covers less calendar time. US equity activity comes from Cboe EDGX; venue and RTH/ETH session choices can change volume-based results.
Quant supports code generation and chart backtesting. A generated script does not automatically perform an independent validation study, reproduce historical fundamentals, or establish realistic live fills. Maintain the chronological splits and research record explicitly. Native Quant research should also be distinguished from the separate TradingView toolkit and Backtesting Assistant workflows.
Read performance after costs
Win rate alone is insufficient. Consider average winning and losing amounts, total net profit, drawdown, trade count, and concentration of returns. Use consistent position sizes and measurement periods when comparing results.
| Illustrative 100-trade sample | Calculation | Result |
|---|---|---|
| 55 winners averaging $120 before costs | 55 × $120 | $6,600 |
| 45 losers averaging $100 before costs | 45 × $100 | −$4,500 |
| Gross trading profit | $6,600 − $4,500 | $2,100 |
| $12 total round-trip cost per trade | $2,100 − (100 × $12) | $900 net |
| Alternative cost assumption: $25 per trade | $2,100 − (100 × $25) | −$400 net |
The same entries and exits can change from profitable to unprofitable under a different cost assumption. This example illustrates sensitivity, not a required sample size. One hundred trades concentrated in one market move can contain less independent evidence than the count suggests.
Drawdown depends on the path of returns, so it cannot be calculated from the win count and average payoff alone. An observed maximum drawdown is also not a ceiling on future losses.
What live paper forward testing adds
Live paper testing observes new signals without placing real-money orders. It can reveal late data, changing signals before bar close, missed notifications, incorrect sizing, and a workflow that is difficult to follow consistently.
It also limits hindsight: you must record the decision before seeing the outcome. That benefit is lost if you enter only the trades that later looked attractive or delete inconvenient results from the record.
Where simulation falls short
A paper fill is a model of execution. It may not reproduce queue priority, available size, partial execution, rejected orders, market impact, or the price available after a delay. Real-time data does not automatically make simulated trading realistic.
Paper trading can help practice discipline, but it does not reproduce the pressure of losing real capital. It also samples only the market conditions that occur during the observation period. A few quiet weeks do not test how a strategy handles a liquidity shock.
Video: a discussion of forward-testing limitations
This TradersPost discussion examines forward testing and the difficulty of deciding whether a strategy’s apparent advantage is real. Treat it as practitioner commentary. A testing method does not itself generate returns, and its title should not be read as evidence that forward testing guarantees better performance.
Compare the frozen strategy with its prospective record
Use the intended capital, sizing rules, session, and cost assumptions in the paper account. Before starting, define the observation period, the issues that would pause the test, and the evidence required for a review. A rare-signal strategy needs more calendar time than one generating many distinct opportunities.
- Record every eligible signal, including those missed or deliberately skipped.
- Keep signal time, assumed order time, simulated fill, and actual platform response separate.
- Compare the same instrument, session, rule version, and period when investigating a discrepancy.
- Classify differences as data, implementation, execution assumptions, rule compliance, or changed market conditions.
- Start a new version when changing logic; preserve the earlier record.
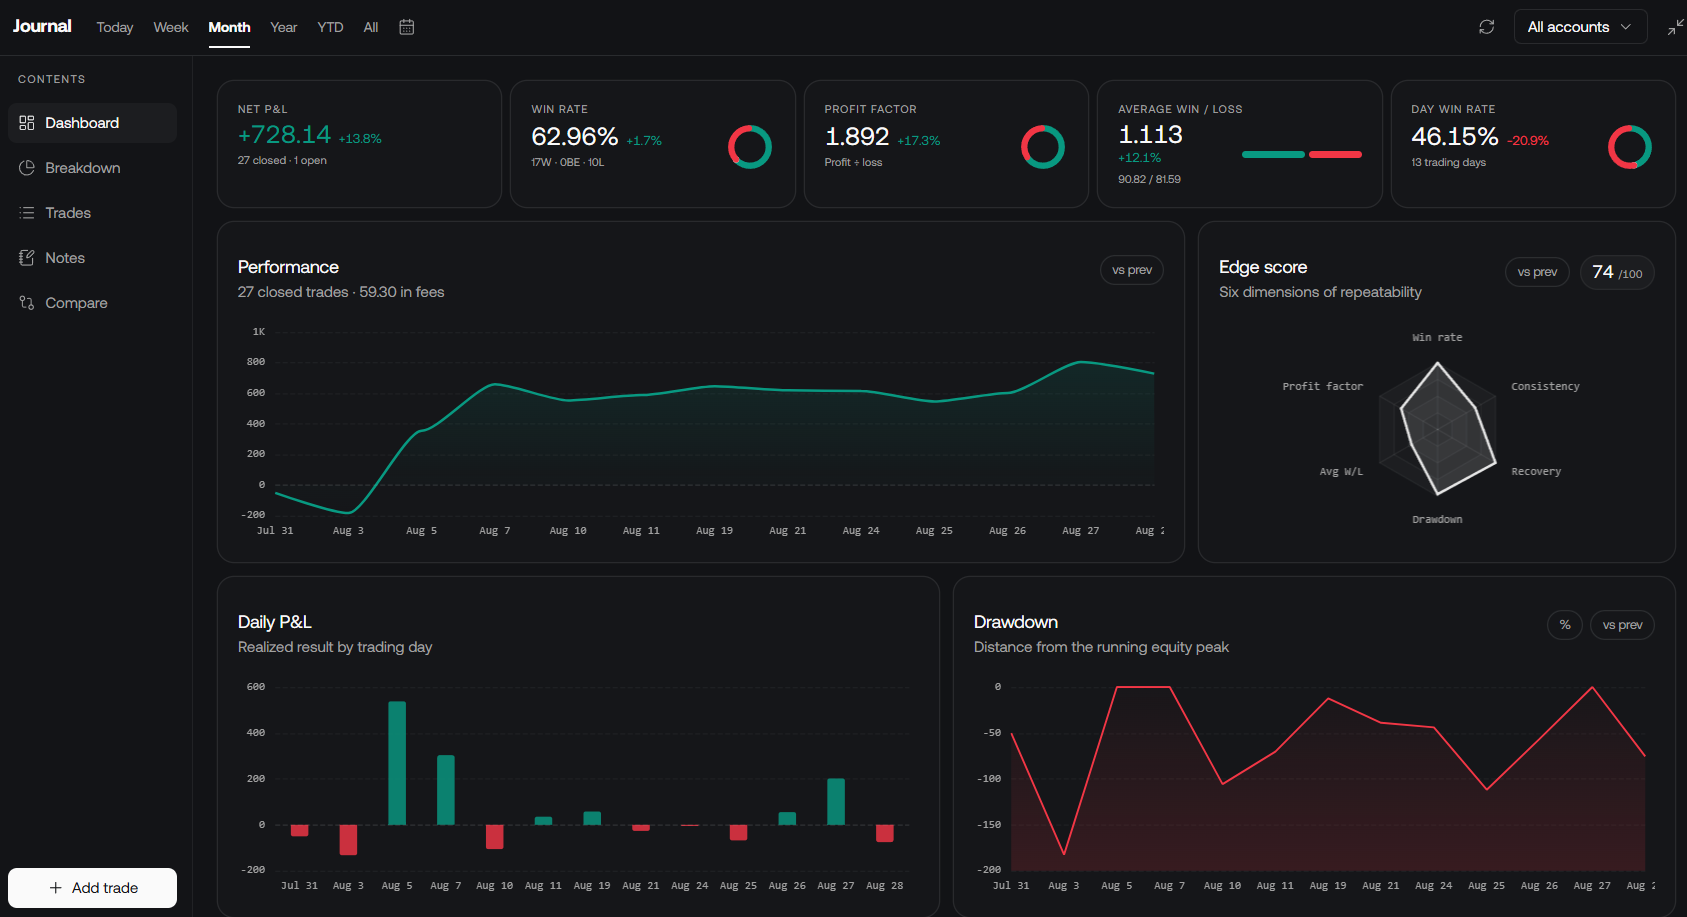
Use the LuxAlgo Journal to maintain a separate manual account for paper fills and attach notes to the review. Keep simulated records distinct from broker fills. The Journal supports recording and analysis; it is not proof that a simulated order could have filled in the live market.
Choose software for the stage of testing
| Tool | Relevant use | Distinction to preserve |
|---|---|---|
| LuxAlgo Quant and native charts | Generate, inspect, and backtest technical strategy code; review trades | Historical chart results require independent validation and prospective observation |
| TradingView Paper Trading | Practice order placement and track positions with virtual funds | A simulated account is different from historical Pine Script® strategy results |
| MetaTrader 5 Strategy Tester | Test and optimize Expert Advisors, including a reserved forward period | The tester’s Forward option uses a later historical segment, not necessarily live paper trading |
| Gainium Paper Trading | Practice supported crypto bot and manual-trading workflows with virtual funds | Check the selected market and simulator assumptions before comparing with real execution |
Backtesting helps investigate the idea and its mechanics. Historical out-of-sample evaluation tests beyond the development data. Live paper observation tests the workflow against new information. Use the differences between those records to diagnose problems rather than assuming future returns should equal a fixed percentage of the backtest.
Read next