Risk-Reward Ratio vs. Win Rate: Key Differences
Risk-reward ratio describes the size of a planned gain relative to a planned loss. Win rate describes how often completed trades actually make money. The first helps evaluate an entry-and-exit plan; the second summarizes the frequency of profitable outcomes. Neither tells you the value of a strategy on its own.
Throughout this guide, 1:2 risk-to-reward means risking $1 for a potential $2 gain. The corresponding reward-to-risk multiple is 2. Keeping these labels explicit prevents a common mistake: reversing the ratio while calculating the win rate needed to break even.
For performance analysis, combine win rate with realized average wins, average losses, and costs. LuxAlgo’s native charts, Quant, and Journal support a workflow for comparing a proposed rule with backtest results and actual trade records.
| Metric | Question it answers | Example | Main limitation |
|---|---|---|---|
| Planned risk-to-reward | What are the intended loss and gain at the chosen exits? | $100 risk and $200 reward = 1:2 | Targets and stops do not guarantee actual outcomes |
| Win rate | What fraction of completed trades were profitable? | 20 wins in 50 trades = 40% | Does not describe the size of wins or losses |
| Realized payoff ratio | How large was the average win relative to the average loss? | $200 average win ÷ $100 average loss = 2 | Depends on the sample, sizing, and accounting |
Understanding the Risk-Reward Ratio
How to Calculate Risk-Reward Ratio
For a simple long trade with a target above entry and a stop below entry:
- Planned risk per share = entry − stop.
- Planned reward per share = target − entry.
- Risk-to-reward notation = planned risk : planned reward.
- Reward-to-risk multiple = planned reward ÷ planned risk.
At an entry of $60.00, a stop of $59.90, and a target of $60.20, planned risk is $0.10 per share and reward is $0.20. The risk-to-reward ratio is 1:2, or a reward-to-risk multiple of 2, before costs.
For a simple short trade, use stop minus entry for risk and entry minus target for reward. Convert price distances into monetary amounts using position size and the instrument’s specifications. A ratio alone does not tell you how much of the account is at risk.
These calculations describe an intended outcome, not an expected or guaranteed return. Partial exits, changed stops, gaps, and slippage can change what is realized. The SEC’s order-types guidance explains why a stop price is not a guaranteed execution price.
Why the Ratio Matters
A larger realized payoff ratio can support positive results with fewer winning trades. But moving a target farther away may also make it less likely to be reached. Drawing a larger reward on the chart does not establish that the strategy can capture it.
Under a simplified model in which every trade is either a win of b risk units or a loss of one risk unit, with no costs or scratch trades, the break-even win rate is 1 ÷ (1 + b).
| Risk-to-reward | Reward-to-risk multiple b | Break-even win rate before costs |
|---|---|---|
| 1:1 | 1 | 50% |
| 1:2 | 2 | 33⅓% |
| 1:3 | 3 | 25% |
| 2:1 | 0.5 | 66⅔% |
Exactly reaching the threshold produces zero gross expectancy in that model. A 32% win rate with wins twice the size of losses produces a loss: 0.32 × 2 − 0.68 × 1 = −0.04 risk units per trade. The threshold rises when costs are included.
What Does Win Rate Mean?
How to Calculate Win Rate
Win rate = winning completed trades ÷ all completed trades × 100%. For example, 20 profitable trades out of 50 completed trades gives a 40% win rate.
Define “profitable” consistently, preferably after relevant costs. A small gross gain may be a net loss. Specify whether a trade means a complete position from flat to flat or an individual partial exit, and handle break-even trades consistently. Open positions should not be silently counted as completed wins.
If the denominator includes scratch trades, the loss rate is not necessarily 1 minus the win rate. For example, 20 wins, 25 losses, and five break-even trades give a 40% win rate and a 50% loss rate across 50 completed trades.
Limitations of Focusing Only on Win Rate
The following hypothetical examples use ten completed trades, average wins and losses as shown, and no costs:
| Wins / losses | Average win | Average loss | Total result |
|---|---|---|---|
| 7 / 3 (70% win rate) | $50 | $100 | 7 × $50 − 3 × $100 = +$50 |
| 4 / 6 (40% win rate) | $300 | $100 | 4 × $300 − 6 × $100 = +$600 |
| 5 / 5 (50% win rate) | $100 | $100 | $0 |
| 7 / 3 (70% win rate) | $100 | $300 | 7 × $100 − 3 × $300 = −$200 |
The first 70% example is slightly profitable before costs; the last is not. If each completed trade incurred $6 in costs not already included, subtract $60 from each ten-trade total. The first result would become −$10. A high win rate can therefore coexist with either a gain or a loss.
Risk-Reward Ratio vs. Win Rate: Key Comparisons
A planned ratio helps frame exits, while observed win rate counts profitable outcomes. The break-even formula tells you a threshold under stated assumptions; it does not predict the actual win rate. Neither metric alone establishes strategy reliability or tells you how frequently to trade.
Position sizing controls the monetary exposure behind the ratio. Larger quantities multiply both potential gain and loss for a simple linear instrument, while the price-based ratio remains the same before costs. See position-sizing methods for risk budgets, stop distance, and practical constraints.
Finding the Balance
Suppose strategy A wins 60% of trades with an average win of 1.5 risk units and an average loss of one. Its gross expectancy is 0.60 × 1.5 − 0.40 × 1 = 0.5 risk units. Strategy B wins 50% with two-unit wins and one-unit losses: 0.50 × 2 − 0.50 × 1 = 0.5 risk units.
These two examples have equal gross expectancy per trade. Shifting between them does not automatically increase profitability. Costs, frequency, holding time, drawdown, and the evidence behind the estimates may still make one preferable. Test the change rather than assuming that a farther target compensates for a lower hit rate.
How to Balance Risk-Reward Ratio and Win Rate
Use Realized Expectancy
Sample expectancy = win fraction × average win − loss fraction × average loss. Use a positive magnitude for average loss and calculate both fractions from the same completed-trade sample. CME’s mathematical expectation lesson explains why outcome frequency must be combined with outcome size.
With a 60% win rate, no scratch trades, $200 average wins, and $100 average losses, the result is 0.60 × $200 − 0.40 × $100 = $80 per trade. If these are gross figures and average costs are $6 per trade, net expectancy is $74. If wins and losses already include those costs, do not subtract them again.
For a simplified win-or-loss model with gross average win W, gross average loss L, and average cost c per trade, the break-even win rate is (L + c) ÷ (W + L). At W = $200, L = $100, and c = $6, that is 106 ÷ 300, or about 35.33%.
For a complete sample using consistent net results, total net P&L divided by the number of completed trades provides a useful cross-check. Positive sample expectancy describes that sample; it does not guarantee future profitability. Small samples, unusually large winners, changing position sizes, and changing market conditions can materially affect the estimate.
Evaluate Changes Without Chasing Metrics
- Entry changes: compare the revised condition with the original, including how many opportunities it removes.
- Exit changes: measure actual average wins and losses, not only the new target distance.
- Sizing changes: separate greater monetary exposure from better signal quality. Keep risk constraints comparable.
- Testing changes: reserve data for evaluation and avoid repeatedly tuning to the same apparent success.
Review drawdown, costs, capital use, and time in trades alongside expectancy. Continual tweaking can fit historical noise. Change rules for an evidence-based reason, record the change, and evaluate it on data that did not guide the decision.
Tools to Review Risk-Reward Ratio and Win Rate
Test the Plan with LuxAlgo Quant
On LuxAlgo’s native charting platform, define the entry, stop, target, and sizing rules before comparing results. Ask Quant to generate the strategy, review its code, and run it on the intended symbol and timeframe. Use Inputs for exposed parameter changes and Quant for changes to the logic.
The native strategy results include performance metrics and a trade log. Set realistic commission and slippage assumptions, inspect representative trades, and compare the realized outcomes with the planned exits. A generated script running without errors does not prove that its fills or calculations match your intent.
Review Actual Results in the Journal
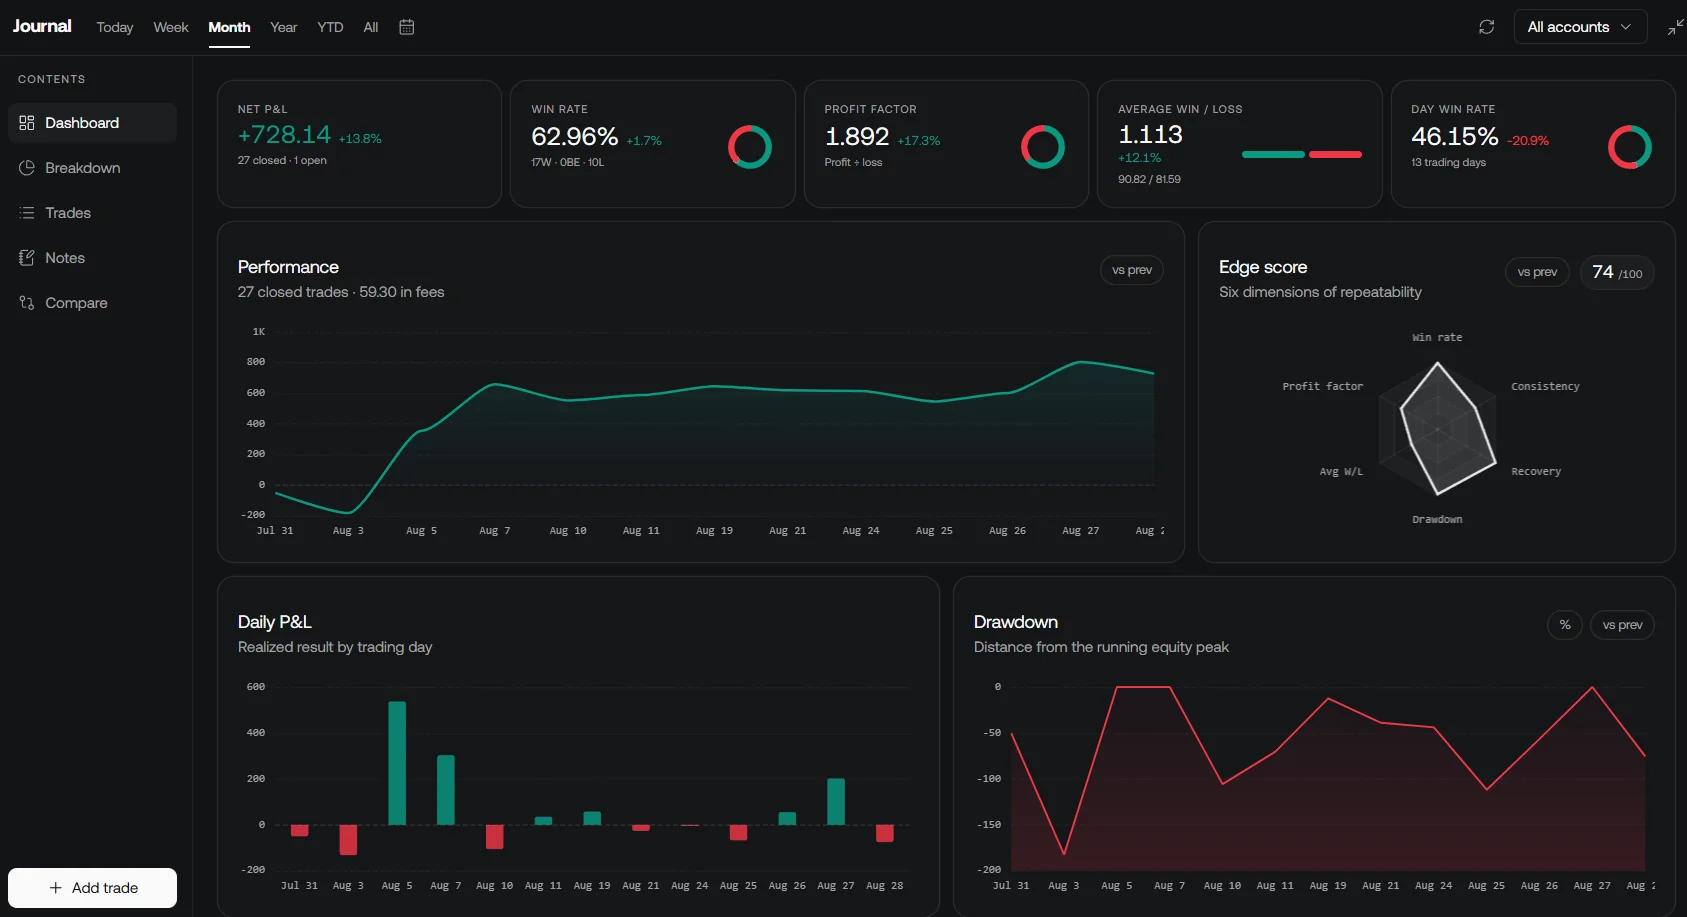
Use the native Journal to review available trade records. It derives completed round trips from fills and distinguishes wins, losses, and break-even trades using net P&L. Manual entry, supported imports, and available broker connections provide different ways to build the record.
Reconcile quantities and fees, then compare the same date range and trade definition across reports. If results diverge from the backtest, investigate execution, costs, rule changes, and data before attributing the difference to discipline or market behavior.
Why Backtesting Matters
A backtest helps reveal how a fully specified rule behaved on the available history. It can reject a seemingly attractive combination of target and stop when too few trades reach the target, or expose results dominated by a small number of large winners.
Use a separate evaluation period and realistic fill assumptions. Compare periods and relevant markets without assuming their results transfer. A profitable historical test is evidence to investigate further, not confirmation that a preferred win rate or ratio will persist.
Putting the Metrics Together
Label the ratio clearly, calculate win rate from consistently defined trades, and use realized net outcomes to assess expectancy. Keep planned targets separate from results actually achieved.
Then compare alternatives under similar risk and cost assumptions. The useful question is how a rule changes the complete distribution of outcomes, including drawdown and rare large losses, rather than whether one headline number looks better.
FAQs
What is the difference between risk-reward ratio and win rate?
Risk-reward ratio compares planned loss with planned gain: $100 risk and $200 reward is 1:2 risk-to-reward. Win rate is the percentage of completed trades that are profitable. To assess performance, combine the observed win rate with realized average wins, average losses, and costs; planned targets alone cannot establish profitability.
Read next