Profit Factor in Trading: Basics Explained
Profit factor is the sum of profits from winning trades divided by the absolute sum of losses from losing trades. It describes how much profit a selected trade sample generated for each dollar lost. A value above 1 means gains exceeded losses on the accounting basis used; it does not establish that a strategy will remain profitable.
For example, $10,000 in winning-trade profits divided by $5,000 in losing-trade losses gives a profit factor of 2.0. That is $2 of winning-trade profit for every $1 of losing-trade loss—not a 200% account return. The difference between those totals is $5,000 before any costs omitted from the trade figures.
- Formula: winning-trade profit ÷ absolute losing-trade loss.
- Interpretation: below 1 means losses exceed gains; 1 means they are equal; above 1 means gains exceed losses in the selected sample.
- Context: check costs, trade count, drawdown, position sizing, and the period tested.
- Workflow: use LuxAlgo’s native strategy viewer for simulated results and the Journal for reviewing recorded trades.
How to Calculate Profit Factor
Step-by-Step Guide to Calculating Profit Factor
Choose one account or strategy, a stated date range, and a consistent trade definition. Use closed trades unless the report explicitly says otherwise. Then calculate:
- Sum the positive profit-and-loss values of winning trades.
- Sum the negative values of losing trades and take the absolute amount.
- Divide the positive total by the absolute negative total.
- Record whether commissions, financing, and other costs are included, and whether open positions are excluded.
The terms gross profit and gross loss usually refer to the aggregate winning and losing totals in this formula. They do not, by themselves, establish whether a particular platform deducts fees before classifying each trade. Check the report’s accounting method and avoid mixing pre-cost gains with after-cost losses.
A Worked Example Including Costs
Consider four hypothetical closed trades. Each has a $5 round-trip fee, already allocated in the final column:
| Trade | P&L before fees | Round-trip fee | P&L after fees |
|---|---|---|---|
| 1 | $200 | $5 | $195 |
| 2 | −$100 | $5 | −$105 |
| 3 | $150 | $5 | $145 |
| 4 | −$50 | $5 | −$55 |
Before fees, winning profits total $350 and losses total $150: $350 ÷ $150 ≈ 2.33. After fees, winning profits total $340 and losses total $160: $340 ÷ $160 = 2.125. Net profit falls from $200 to $180. Deducting all fees from only the numerator would not reproduce this trade-level calculation.
Small winners can become losers after costs, which changes both totals and the win rate. Slippage, borrowing charges, funding, and currency conversion can matter too. For a backtest, model applicable costs; for recorded trades, reconcile the trade figures with the account statement.
How to Interpret Profit Factor Values
| Profit factor | What it establishes | What it does not establish |
|---|---|---|
| Below 1 | Losses exceeded gains in the selected sample | That every future period will lose |
| Exactly 1 | Gains equaled losses on the stated accounting basis | Break-even after costs that were omitted |
| Above 1 | Gains exceeded losses in the selected sample | Future profitability or acceptable drawdown |
| 1.7 or 1.75 | A specific historical gains-to-losses ratio | A universal pass/fail threshold |
| Very high | Gains were large relative to recorded losses | A robust edge without checking the sample |
There is no universal cutoff at 1.75. A profit factor of 1.7 means $1.70 in gains for every $1 in losses under the chosen calculation. Whether it is useful depends on the strategy, execution costs, number of trades, and stability outside the period used to develop it.
If there are no losing trades but positive gains, the denominator is zero. The ratio is not a finite number; software may display infinity, a blank, or another convention. If both totals are zero, the calculation is also undefined. Neither situation proves a perfect strategy. With positive losses and no winning profits, profit factor is zero.
Using Profit Factor to Evaluate Trading
Assessing Strategy Performance
Review profit factor over defined weekly, monthly, or longer periods, but show trade count alongside it. A daily value based on two trades is not comparable evidence to a multi-year sample with many trades. Market regimes, venue, session, and changing position size can all alter the result.
Inspect concentration. Suppose $4,000 of a $10,000 winning total comes from one trade while total losses are $5,000. The overall profit factor is 2.0; removing that single winner as a sensitivity check gives $6,000 ÷ $5,000 = 1.2. Keep the real trade in the actual report. The separate calculation reveals dependence on an outlier rather than justifying deletion of inconvenient observations.
Do not average period-level profit factors to obtain the combined value. If period A has gains of $100 and losses of $50, its value is 2.0. If period B has gains of $100 and losses of $200, its value is 0.5. The combined result is $200 ÷ $250 = 0.8, not the arithmetic average of 1.25.
Profit Factor in Risk Management
Profit factor does not describe the order of wins and losses. The same trade results can arrive in a different sequence and produce a very different drawdown. It also does not show how much capital was committed, the size of open losses, or the risk of an infrequent severe event.
Use it alongside maximum drawdown, net profit, exposure, and the loss distribution. Review open positions separately from closed-trade statistics. A high ratio cannot justify ignoring leverage, correlated positions, liquidity, or the possibility that a stop fills beyond its trigger.
Comparing and Choosing Strategies
A strategy with a profit factor of 2.5 has more gains per dollar lost in its sample than one with 1.8. That alone does not make it the better choice. It may have fewer trades, a much smaller net profit, larger drawdowns, greater capital requirements, or unrealistic fills.
Compare strategies over the same dates and data, with consistent costs, sizing, trade grouping, and accounting currency. Report differences that cannot be standardized. Multiplying every trade’s P&L by the same positive factor leaves profit factor unchanged while increasing the dollar gains and losses; changing size selectively can change the ratio itself.
Tips for Improving the Research Process
Combine Profit Factor with Other Metrics
The following measures answer different questions:
- Win rate: what proportion of closed trades ended positive? State how breakeven trades are counted.
- Average win and average loss: how large were realized winners and losers? This is different from the planned target-to-stop ratio.
- Expectancy: what was the average P&L per trade on the same accounting basis?
- Maximum drawdown: how far did equity fall from a prior peak? Check whether the calculation includes open-position fluctuations.
- Trade count and net profit: how much evidence and absolute profit sit behind the ratio?
When there are no breakeven trades, profit factor can also be written as (win rate × average win) ÷ (loss rate × average loss), with average loss expressed positively. At a 40% win rate, a $300 average win, and a $100 average loss, it is (0.4 × 300) ÷ (0.6 × 100) = 2.0. Expectancy is $120 − $60 = $60 per trade on that same basis. A win rate below 50% can therefore coexist with positive expectancy.
Define Trade Quality Before the Outcome
Replace “take better trades” with a condition you can test: a specified session, a liquidity requirement, or an explicit entry and exit rule. Compare the baseline with the added condition while keeping the other assumptions fixed. Fewer trades do not automatically mean a higher profit factor or better total results.
A tighter stop may reduce some losses but create more stopped-out trades. A farther target may increase average wins but reduce their frequency. Evaluate the resulting distribution rather than assuming an attractive planned reward-to-risk ratio will be realized.
Regularly Review Without Chasing the Best Backtest
Keep a record of the rules and parameter combinations tested. Selecting the highest historical ratio from many variations can fit noise, especially when the winning version has few trades. Check nearby parameter values and a later period that was not used to choose the settings.
Use scheduled reviews to detect changes, not to rewrite the strategy after every loss. A higher in-sample profit factor is a research result to investigate, not a promise of improvement. Record unsuccessful tests so the final result is not presented as though it were the only idea tried.
Tools for Analyzing Profit Factor in LuxAlgo
Build and Run a Strategy with Quant
Start in native LuxAlgo charts. Quant, our coding agent, can help turn explicit entry, exit, sizing, and cost assumptions into a strategy script. Inspect the generated code, confirm that it uses only information available at each decision, and run it manually on the intended symbol and time frame.
The native strategy viewer reports profit factor alongside net profit, trade count, win rate, and maximum drawdown. Inspect the Trades Log and the distribution of results instead of selecting a run from the headline ratio alone. Set realistic commission and slippage, and use standard chart prices: averaged Heikin Ashi prices are not reliable executable-fill assumptions.
Keep the script, inputs, simulation properties, data, and dates with your results. Test a separate period and examine individual trades. Do not assume that prompting Quant automatically searches for or proves the best strategy.
Review Recorded Trades in the Journal
Use the LuxAlgo Journal to review recorded fills and their derived trades. Keep simulated results separate from actual account activity. Check the selected account and date range, reconcile fees and fills, and investigate discrepancies before comparing its metrics with a backtest.
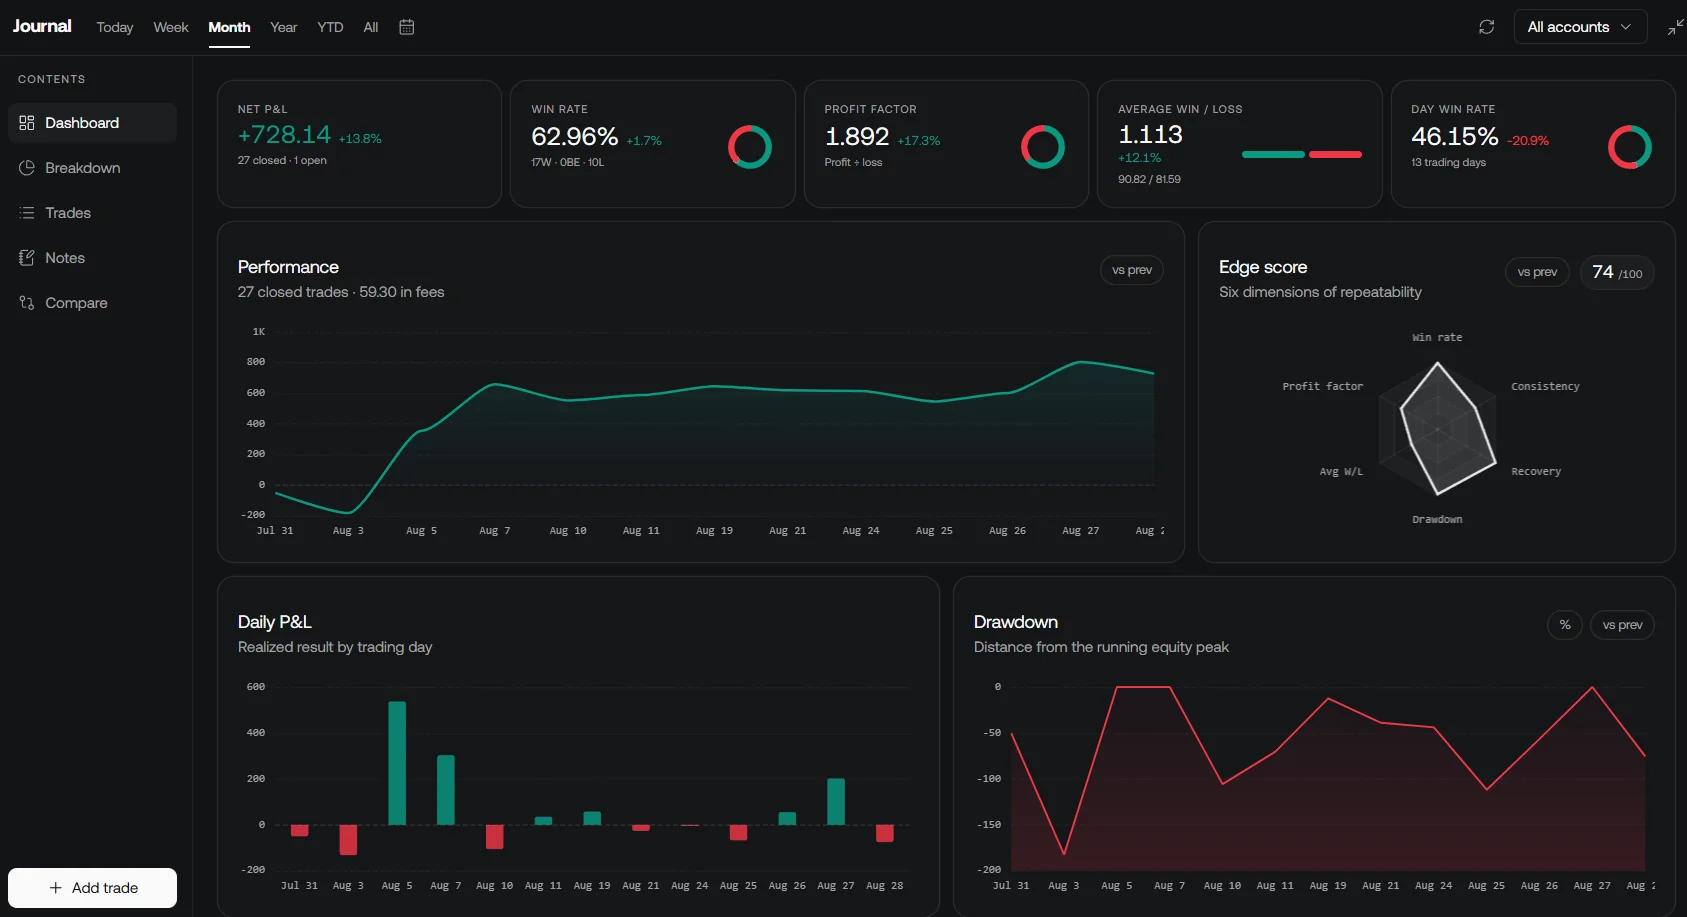
The Journal groups fills into completed round trips and distinguishes open, winning, losing, and breakeven trades. Its dashboard provides the broader review context. Make sure the trade grouping and cost treatment match before expecting another report to produce the same ratio.
Conclusion: Use the Ratio with Context
Profit factor is a useful summary of gains relative to losses, not a standalone verdict. Calculate it consistently, include applicable costs, and examine sample size, concentration, drawdown, and out-of-sample behavior. The practical goal is a reproducible evaluation process—not reaching an arbitrary threshold or maximizing one historical number.
FAQs
Is a 1.7 profit factor good?
It means the selected sample produced $1.70 in gains for every $1 in losses on the stated accounting basis. There is no universal 1.75 cutoff. Assess costs, trade count, drawdown, and performance on data not used to choose the strategy.
How can I improve my profit factor?
Test specific changes to entry, exit, sizing, or cost assumptions against a documented baseline. Check whether an apparent improvement survives a separate period and preserves acceptable drawdown and trade count. Fewer trades or tighter stops do not guarantee improvement.
What role does backtesting play?
Backtesting estimates how explicit rules would have behaved on historical data under stated execution assumptions. In native LuxAlgo, inspect the strategy code and run it manually, then review individual trades and costs. A strong historical result does not guarantee future performance.
What does a profit factor of 2 mean?
Winning-trade profits were twice the absolute losing-trade losses in the selected sample. It does not mean the account earned 200%, and it does not describe drawdown or the sequence of trades.
What if a strategy has no losing trades?
With positive gains and zero losses, profit factor is not a finite number because its denominator is zero. A platform may show infinity or leave it blank. Check the number of trades and the test period rather than treating this as evidence of a risk-free strategy.
Read next