5 Steps to Build Rule-Based Trading Strategies
A rule-based trading strategy turns an idea into decisions that can be repeated, tested and reviewed. It specifies when a trade is allowed, how a position is sized, what closes it and when trading pauses. Written rules can reduce improvisation, but they do not remove emotion or guarantee profitable results.
Use LuxAlgo’s native charts and Quant, our coding agent, to move from a clear specification to a strategy you can inspect. The five steps below connect rule design, historical data, backtesting, refinement and validation without treating a good backtest as permission to automate live trades.
Step 1: Write Rules That Leave Little Room for Interpretation
Start with the decisions your strategy must make. Your available capital, time commitment, acceptable exposure and ability to handle drawdowns constrain the design. A desired monthly return is an aspiration, not evidence that a rule can produce it.
| Decision | What to specify |
|---|---|
| Market and schedule | Instrument, venue, timeframe, session and when you can monitor it |
| Entry | The exact condition and whether it uses a completed candle |
| Exit | Stop, target, opposite signal, time limit or a defined combination |
| Position size | Quantity calculation, capital limits and permitted number of positions |
| Exceptions | Missing data, earnings or news exposure, abnormal spreads and missed signals |
| Pause and review | Conditions that stop new entries and the process for restarting |
“Buy strong momentum” is not an executable rule. “On a completed daily candle, enter long when the 20-period EMA crosses above the 50-period EMA” is more specific, but still needs an order-timing policy, exits and sizing.
Indicators should have distinct jobs. A moving average may supply a trend condition, RSI a momentum condition and volume an activity filter. Adding all three does not automatically provide independent evidence. Start with a simple baseline and add a filter only if a fair comparison supports keeping it.
A Practical Strategy Specification
For a hypothetical moving-average research strategy, document the following before testing:
- Use one chosen stock on standard daily candles and record its data source and session.
- Generate a long candidate when the 20 EMA crosses above the 50 EMA on a completed bar; allow only one long position and no additional entries while it is open.
- Define the simulated entry timing, for example the next available bar’s open under the chosen fill model.
- Set an initial stop at a distance of twice the 14-period ATR measured on the signal bar, with the stop price referenced to the eventual entry fill.
- Exit on the stop or a completed bearish EMA crossover, according to the documented order-handling policy.
- Calculate quantity from the planned risk distance, then apply capital and margin constraints. Document what happens when costs or gaps exceed the assumed risk.
These are illustrative rules, not a recommended strategy. A model must also specify when the stop becomes active and how intrabar events are ordered. Do not assume the same candle’s high, low and close reveal an executable sequence.
Suppose a hypothetical account assigns a $100 price-risk budget to a trade. A $2 stop distance permits 50 shares before costs and constraints; a $4 distance permits 25. Allocating 10% of an account to a position is a different calculation and does not mean the maximum loss is 10% or any smaller fixed amount.
Step 2: Select Data That Matches the Question
Historical data lets you examine how a rule behaved under recorded conditions. It does not ensure the rule will handle conditions that have not occurred or that the simulation represents attainable fills.
Record the feed, venue, timeframe, session, dates and adjustment policy. Check gaps, duplicate bars, timezone changes and the handling of stock splits, dividends or futures rolls where relevant. Keep price series internally consistent rather than mixing an adjusted close with incompatible highs and lows.
There is no universal minimum of five to ten years, nor a universal rule that two months is enough for day trading or one year for swing trading. The useful sample depends on trade frequency, holding period, data quality, changes in market structure and the range of conditions covered. A long calendar period with very few trades can still provide weak evidence.
Include enough earlier bars for indicator calculations to warm up. Identify development and evaluation periods before selecting parameters. If testing a stock universe, consider securities that delisted or left the universe rather than choosing only current survivors.
Separate three questions: whether the data is suitable, whether the trading rules are implemented correctly, and whether the resulting strategy performs well. A clean dataset cannot answer the other two by itself.
Step 3: Build and Review the Backtest with Quant
Describe the strategy to Quant using the rules you wrote. Include entries, exits and risk conditions. Review Code, then Run the strategy on the native chart. An indicator plots information; a strategy needs simulated trade logic to produce a backtest.
Inspect plotted entries and exits against the specification. Check some losing trades and periods with no entry as well as favorable examples. If the editor contains an indicator, its Backtest action can ask Quant to convert it into a strategy; review the resulting trade rules rather than assuming they match your intent.
Use Inputs for exposed parameters and Properties for capital, size, pyramiding, commission, slippage and margin. Change the logic through Quant when necessary. Fixing a syntax or runtime error does not prove the strategy is economically sound.
| Evidence | What it helps you assess |
|---|---|
| Net result and costs | Whether simulated gains survive the chosen execution assumptions |
| Trade count and holding time | How much evidence supports the result and how the strategy uses capital |
| Average win and loss | The size of outcomes behind the win rate |
| Maximum drawdown | The largest measured decline from an equity peak in this sample |
| Profit factor | Gross profit relative to gross loss under the report’s accounting |
| Individual trades | Unexpected fills, outliers, missed rules and dependence on a few outcomes |
The native backtest viewer separates Performance, Trades Analysis and Trades Log. Star a run to preserve its script, symbol, timeframe, inputs and backtest properties. Keep an experiment log alongside saved runs so the reason for each change remains clear.
Do not confuse the planned target-to-stop ratio with the realized average win-to-loss ratio. Partial exits, trailing stops and gaps can make them very different. If calculating Sharpe ratio separately, specify return frequency, annualization and the risk-free-rate convention; use consistent assumptions when comparing strategies.
Step 4: Refine One Hypothesis at a Time
Review where the baseline fails before changing it. A strategy might depend on one market phase, suffer from execution costs or generate most of its profit from a few trades. Those are different problems and may not be fixed by changing an indicator length.
For the moving-average example, compare one change at a time: the fast period, the stop multiplier, or a clearly defined RSI filter. Keep the remaining rules, dates and cost assumptions fixed. If you change all three together, you can compare complete variants but cannot attribute the result to one component.
Record each trial, including rejected ones. Look for a reasonable neighborhood of settings rather than an isolated historical peak. More trials create more opportunities to find a lucky result; choosing the winner does not remove that selection effect.
Volatility-based sizing, trailing exits and news filters can be useful design choices, but they also add assumptions. Define their timing and compare them against the simpler baseline. Complexity should earn its place through evidence rather than grow merely because you feel more confident.
Out-of-sample evaluation can help expose overfitting, but it does not make a strategy immune to it. Repeatedly checking the same evaluation period while retuning turns that period into development data. Quant helps implement the comparison; the research design still determines what the result can support.
Step 5: Validate the Workflow Before Increasing Exposure
| Stage | Question to resolve | Evidence to retain |
|---|---|---|
| Separate historical evaluation | Does the frozen rule behave acceptably outside the selection period? | Dates, unchanged configuration, costs and results |
| Sensitivity review | What happens with worse fills, other suitable instruments or nearby parameters? | Defined scenarios and material differences |
| Paper trading | Can the signals, orders and review process be followed in real time? | Signal timestamps, simulated fills, missed events and deviations |
| Limited live evaluation, if chosen | How do actual costs and execution differ? | Broker fills, fees, rule adherence and pause decisions |
Paper trading evaluates the workflow without risking trading capital, but its fills and psychological conditions differ from live trading. A fixed starting size of 25–30% of an eventual position is not a universal safe rule. Any decision to trade live should fit the actual risk budget, liquidity and ability to monitor the system.
Define when new entries pause: a data outage, unexpected orders, risk-limit breach or a result that requires investigation. Also define how open positions are handled; stopping new trades does not automatically close existing exposure. Review at planned intervals instead of changing the rules impulsively after every loss.
Keep alerts separate from execution. Confirm that the chosen alert mechanism supports the intended script, symbol and condition, and test its delivery. A notification or webhook is not proof of a broker fill.
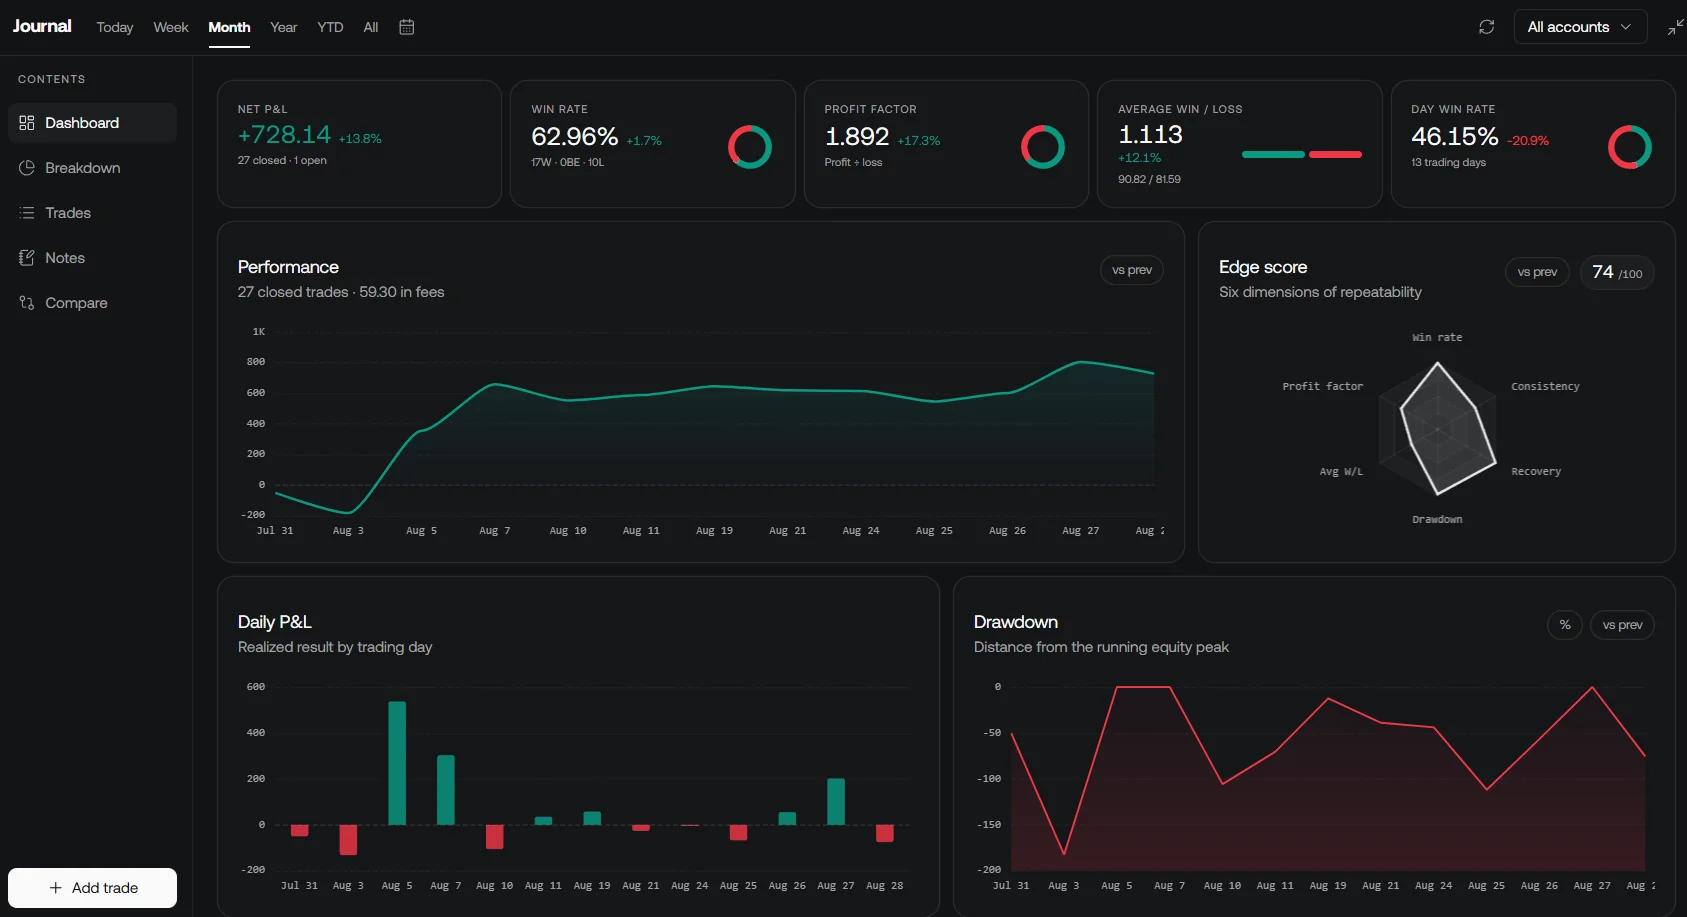
The LuxAlgo Journal lets you review recorded fills, trades and notes alongside charts. It is account-level, so switching workspaces preserves the same journal data. Use tags or notes to distinguish strategy versions and rule deviations, with a separate log for research trials that never became trades.
A repeatable process makes decisions easier to examine. It does not ensure steady returns, remove the need for judgment or make constant retuning beneficial. Keep the strategy version, the evidence and the reason for each decision connected.
FAQs
How does rule-based trading work?
It uses predefined conditions for entries, exits, sizing and exceptions, then evaluates whether those conditions are followed and how they perform. Rules can reduce improvisation, but people still choose the assumptions and may override them. A repeatable strategy is not necessarily a profitable one.
How long should you backtest a trading strategy?
Use a period that provides enough relevant trades and a meaningful range of conditions for the strategy, with suitable data quality and indicator warm-up. There is no universal number of months or years. Reserve a separate evaluation period before selecting parameters, and consider whether older data still represents the market and execution conditions being studied.
Read next