Concept
Trading Sessions
Trading Sessions, also known as Sydney/Tokyo/London/New York, overlaps, are Time, Sessions & Seasonality concepts. The Library holds 9 implementations, each one a working definition you can pull into Quant.
Top Trading Sessions indicators
The top custom implementations, built on the original standard Trading Sessions formula.
9 total
Every Trading Sessions implementation here is strategy-ready: open one in Quant, set your rules, and it backtests automatically.


What are Trading Sessions?
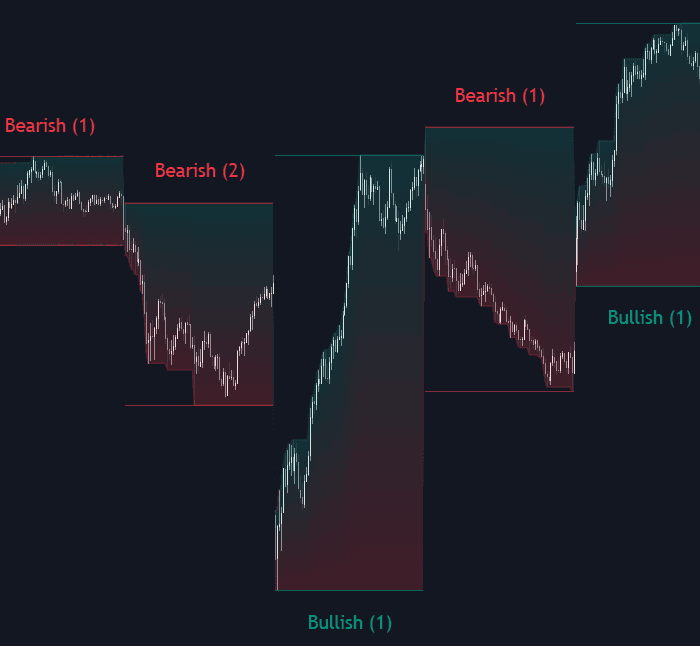
Trading sessions are the recurring daily windows when each major financial center is active: Sydney and Tokyo through the Asian hours, London through the European morning and afternoon, New York through the US day. In 24-hour markets like forex and futures, the calendar day is really a relay of these regional sessions, and charts commonly shade them as boxes so the trader can see at a glance which regional desks are active.
Sessions matter because liquidity and volatility are not distributed evenly around the clock. The Asian hours tend to be quieter and rangebound for most non-yen pairs, London frequently sets one extreme of the day's range, and the London-New York overlap is typically the most liquid stretch of the day. Equities and index futures add their own split between the cash session and overnight trade (RTH vs ETH). Boundaries are conventions, not rules: exact times vary by source and shift with daylight saving.
For a trader the session map is baseline context: the same breakout signal means something different in a thin Asian lunch hour than five minutes after the New York open. Session opens concentrate order flow, session extremes become reference levels, and time-based frameworks such as ICT killzones are refinements of this one idea. All of it describes statistical tendencies with plenty of exceptions, not a schedule the market must obey.
How to read Trading Sessions on a chart
Most platforms offer session shading; the real work is choosing sensible boundaries and tracking what each window leaves behind.
- 1Fix your conventions. A common FX reading runs Tokyo through the Asian morning, London from around 08:00 UK time, and New York from around 08:00 ET, with the US equity cash session at 09:30 to 16:00 ET. Sources differ, so pick one definition and keep it consistent.
- 2Shade each session and note the overlaps. The London-New York overlap is the one most traders isolate, since both centers are trading at once.
- 3Track each session's open, high, and low as it completes. The Asian range, the London extreme, and the New York open all become reference levels for later windows; how often those extremes get revisited is its own field of study (session high/low statistics).
- 4Watch the handoffs. Volume and range typically expand into the London and New York opens and fade through the New York afternoon into the Sydney open, and daylight saving moves the overlaps twice a year.
How traders use it
- As a time filter: many intraday strategies only take signals inside chosen windows, for example the London-New York overlap, on the logic that liquidity is deepest and moves carry follow-through there; ICT killzones are a formalized version of this filter.
- As a source of levels: the Asian session range is a classic reference for London traders, who look for either a clean breakout or a liquidity sweep of its extremes that reverses, and prior session highs and lows are watched as session liquidity that later windows often gravitate toward.
- As a volatility model: stops, targets, and position sizes tuned to session-specific volatility rather than a single daily average, since a range measure taken across all hours blends quiet Asian trade with the New York open. Intraday time-of-day effects quantify these patterns.
- As anchors for indicators: session VWAP resets at each session open, and session-anchored opens, midpoints, and volume profiles frame where value is being built within the current window.
Trading Sessions vs related concepts
Killzones: Killzones are ICT's narrower sub-windows inside the sessions, such as the first hours of London and New York, chosen for setup frequency. Session boxes describe the whole regional day; killzones deliberately exclude most of it.
RTH vs ETH: RTH vs ETH is the exchange-market version of the same idea: one venue's official cash hours against everything traded around them. Trading sessions describe the global relay of financial centers across a 24-hour day.
Opening Range & ORB: The opening range is a level structure built in the first minutes after one specific open. Sessions are the schedule itself, and each session open can host its own opening range.
Session Open/close Behaviors: That concept covers recurring patterns at the boundaries themselves: gaps, opening drives, and closing rotations. This page covers the windows: when sessions run, how they overlap, and what that implies for liquidity.
More Trading Sessions implementations
Concept family
Time, Sessions & Seasonality
32 concepts mapped · 32 in the Library
Trading Sessions FAQ
Turn Trading Sessions into a trading strategy.
Take any implementation from this page into Quant, then build on it, backtest it on real data, and keep refining it in conversation.