Beta
 By LuxAlgoApr 5, 2026
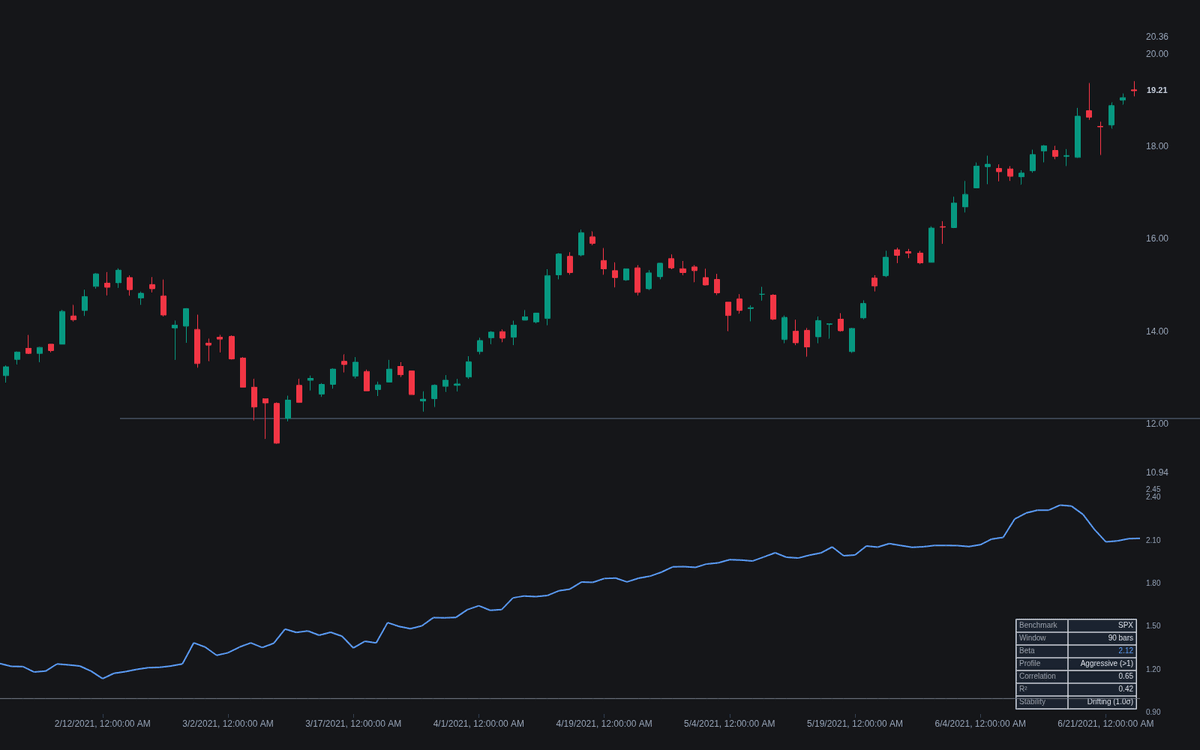
Beta is the definitive clean build of the beta statistic as a chart tool: bar-to-bar returns of the symbol and a chosen benchmark are regressed over a rolling window, and the slope is plotted with a gradient fill, a dashed Market Beta (1.0) line, a dotted Zero Level, and an optional shaded band across the defensive 0–1 region. A dashboard adds the companion numbers a raw slope needs: correlation, R², and a stability read that flags when the estimate drifts from its own average.
How to Trade the Beta?
- Beta above 1: benchmark moves arrive amplified, an aggressive profile arguing for smaller size when the index is volatile.
- Beta inside the shaded 0–1 band: moves arrive damped, the defensive region where index-level noise matters less.
- Beta below 0: the symbol has leaned against the benchmark. Hedge arithmetic reverses, and zero-line crosses fire their own alerts.
- Stability says Drifting: the reading has moved more than one sigma from its window mean; re-check any beta-scaled hedge before trusting the number.
Beta Settings
- Benchmark (default SP:SPX): the index returns are regressed against; crypto workflows typically substitute a Bitcoin ticker.
- Window Length (default 252): rolling estimation window, roughly a trading year of daily bars; shorter tracks regime shifts faster but drifts more.
- Source (default close): price series for both return streams.
- Return Type (default Simple): simple percent returns, or log returns when compounding consistency matters.
- Show Dashboard (default on) with location and size.
- Style: beta color, Gradient Fill (default on), reference line colors, and Shade Defensive Band (0-1) (default on).
Frequently Asked Questions

Original indicatorBuilt in-house by LuxAlgo
The Library is free. Quant makes it yours.
Pull any concept or indicator into Quant: rebuild it, retune it, or turn it into a backtested strategy of your own.