RSI of Other Sources
Wilder's RSI is usually described as a price indicator, but the formula is really a general-purpose transform: it takes a series, splits its bar-to-bar changes into gains and losses, smooths each side, and maps their ratio onto a bounded 0 to 100 scale. They are Momentum & Oscillators concepts. The Library holds 1 implementation, ready to run on Vela.
RSI of OBV, of volume
Top RSI of Other Sources indicator
The top custom implementation, built on the original standard RSI of Other Sources formula.
1 total
From studying RSI of Other Sources to trading it: open the implementation below on Vela, then build a strategy on it with Quant and backtest it.
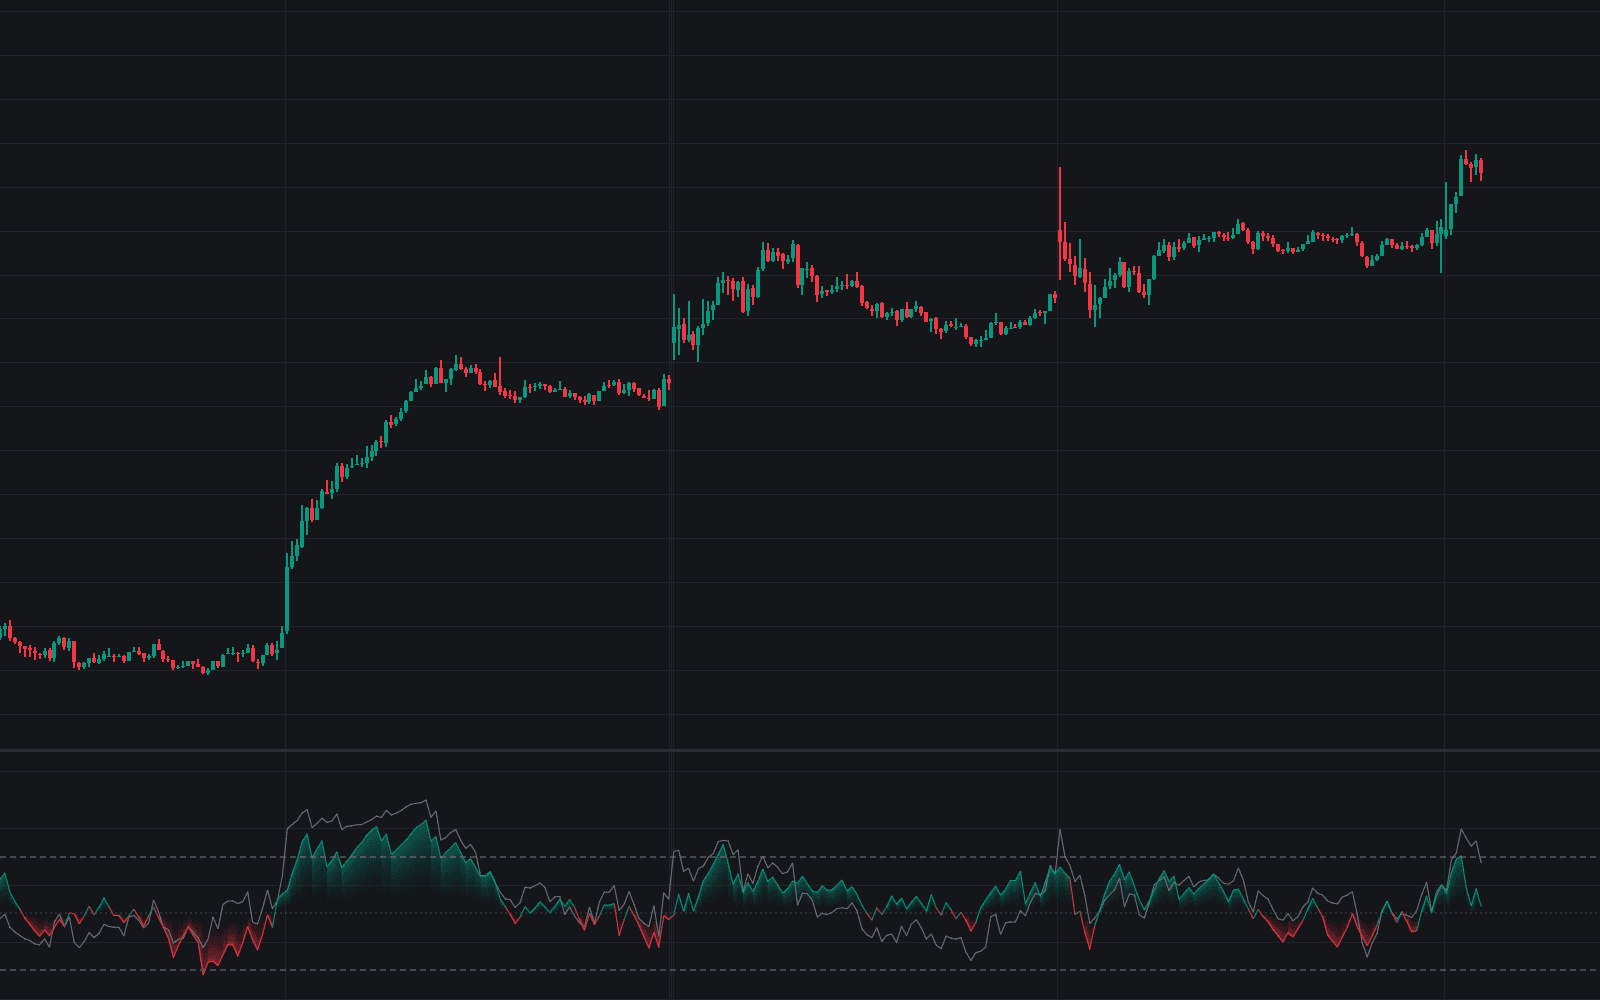
What is RSI of Other Sources?
Wilder's RSI is usually described as a price indicator, but the formula is really a general-purpose transform: it takes a series, splits its bar-to-bar changes into gains and losses, smooths each side, and maps their ratio onto a bounded 0 to 100 scale. RSI of other sources is the practice of feeding that formula something other than the close: OBV, raw volume, a moving average of price, distance from VWAP, even another oscillator. The arithmetic never changes; only the question being asked does.
Wilder published RSI in 1978 as a close-based indicator, but nothing in the arithmetic ties it to closes, and later designers exploited that freedom. Gene Quong and Avrum Soudack folded volume into the gain and loss sums to create the Money Flow Index, and Larry Connors applied a short RSI to the length of up and down streaks inside ConnorsRSI. Once charting platforms exposed the source field as a free input, the practice became a one-click experiment, which is why public libraries now hold RSIs of OBV, VWAP distance, and market-breadth series.
Each input answers a different question. RSI of OBV asks whether cumulative volume flow is accelerating or stalling, which matters precisely when price and participation disagree. RSI of a smoothed input, such as a moving average of close, trades speed for fewer whipsaws. RSI of momentum or ROC reads acceleration rather than direction. The common thread is normalization: unbounded series like OBV or volume become comparable 0 to 100 lines with workable thresholds.
The honest caveat is that the familiar 70/30 levels were calibrated on price, and a derived series can spend far more or far less time at extremes, so overbought and oversold thresholds need rechecking per source. The signal vocabulary needs the same care: a 50-cross on an RSI of volume says participation is expanding, not that price is rising. Derived lines are direction-agnostic lenses on their own series, which is why most workflows pair them with a price-based read instead of trading them alone.
How to build and read an RSI of another source
Most charting platforms expose this through the RSI source input; the steps below keep the result honest.
- 1Add a standard RSI and switch its source from close to the target series: another indicator's output such as OBV or a moving average, or a raw series such as volume.
- 2Scan the derived line across long history and note where it actually tops and bottoms, and how long it pins at extremes.
- 3Set thresholds from that observed range rather than keeping 70/30; a line that lives between 45 and 80 needs its own bands.
- 4Plot price RSI alongside and read agreement or disagreement; the derived line earns its place by confirming or contradicting the price-based view.
How it's calculated
This is the standard RSI computed on an arbitrary input series (volume, OBV, a spread, another indicator) instead of close, measuring the momentum of that series on a 0 to 100 scale.
The math is identical to standard RSI with close replaced by the chosen source; lines 3 and 4 are Wilder's smoothing (RMA), and some platforms offer SMA or EMA smoothing variants.
When AvgD_t = 0 the RSI is set to 100, and to 0 when AvgU_t = 0.
Non-price sources can shift the indicator's typical range, so the usual 70/30 thresholds may need recalibration.
How traders use it
- As participation confirmation: an RSI computed on OBV or cumulative volume delta gives a bounded read of buying and selling pressure, and its agreement or disagreement with price RSI flags moves that lack volume support.
- As a quieter signal line: running RSI on a moving average of price filters one-bar noise, so 50-crosses and threshold exits fire less often but later; the added lag is the price of the filter.
- As a divergence source: regular divergence between price and an RSI of a volume series is read as effort failing to confirm result, flagged on a bounded scale.
- As the normalization step inside composite oscillators: once every input lives on the same 0 to 100 scale, components can be averaged or voted without one series dominating by sheer magnitude.
- As raw material for further transforms: a derived RSI can be post-processed with the Inverse Fisher Transform to sharpen its extremes, or rescaled against its own range the way Stochastic RSI treats price RSI.
RSI of Other Sources vs related constructions
RSI: The baseline: the same gain/loss arithmetic applied to closing price. Everything in this family swaps the input series while keeping Wilder's math intact.
Stochastic RSI: The mirror-image construction: instead of RSI applied to another series, it is another transform (the stochastic) applied to RSI, rescaling RSI to its own recent range.
Volume-weighted MACD: The same instinct, volume-aware momentum, engineered differently: it rebuilds MACD's moving averages with volume weighting instead of running RSI over a volume series. Comparing the two shows how much construction choices shape a signal.
RSI of Other Sources FAQ
Turn RSI of Other Sources into a trading strategy.
Open the implementation from this page in Vela. Quant, our coding agent, builds the strategy with you and backtests it on real data.
Browse this familyMomentum & Oscillators85 concepts mapped · 85 in the Library
- 5/35 Oscillator
- Accelerator Oscillator
- Accumulative Swing Index
- Adaptive Stochastic
- Adaptive/dynamic RSI
- APO
- Awesome Oscillator
- Balance of Power
- Bill Williams Profitunity
- Cardwell Positive/negative Reversals
- CCI
- Center of Gravity
- Centerline Regime
- Chande Forecast Oscillator
- Chande Momentum Oscillator
- Connors RSI
- Constance Brown Studies
- Coppock Curve
- Cyber Cycle
- Detrended Price Oscillator
- Disparity Index
- Divergence Variants & Confirmation
- Double Stochastic
- DSS Bressert
- Dynamic Momentum Index
- Elder Impulse System
- Elder Ray
- Elegant Oscillator
- Embedded Readings
- Ergodic Oscillator
- Firefly Oscillator
- Fisher Transform
- Gator Oscillator
- Hidden Divergence
- Impulse MACD
- Intraday Momentum Index
- Inverse Fisher Transform
- Know Sure Thing
- Laguerre RSI
- MACD
- MACD-V
- Momentum
- Momentum Expansion vs Contraction
- Momentum Thrust
- Oscillator of Oscillator
- Oscillator Swing Failure
- OsMA
- Overbought/oversold
- Polarized Fractal Efficiency
- PPO
- Premier Stochastic
- Pretty Good Oscillator
- Psychological Line
- QQE
- Qstick
- Rahul Mohindar Oscillator
- Rainbow Oscillator
- Reflex/Trendflex
- Regular Bullish/bearish Divergence
- Relative Momentum Index
- Relative Vigor Index
- ROC
- ROC-of-ROC
- RSI
- RSI Bands
- RSI Failure Swing
- RSI of Other Sources
- RSI Range Rules
- RSI-2
- Schaff Trend Cycle
- Special K
- Stochastic Momentum Index
- Stochastic Oscillator
- Stochastic Pop
- Stochastic RSI
- Swing Index
- Traders Dynamic Index
- TRIX
- True Strength Index
- Ultimate Oscillator
- Volume-weighted MACD
- Wave Trend Oscillator
- Williams %R
- Woodies CCI Conventions
- Zero-lag MACD